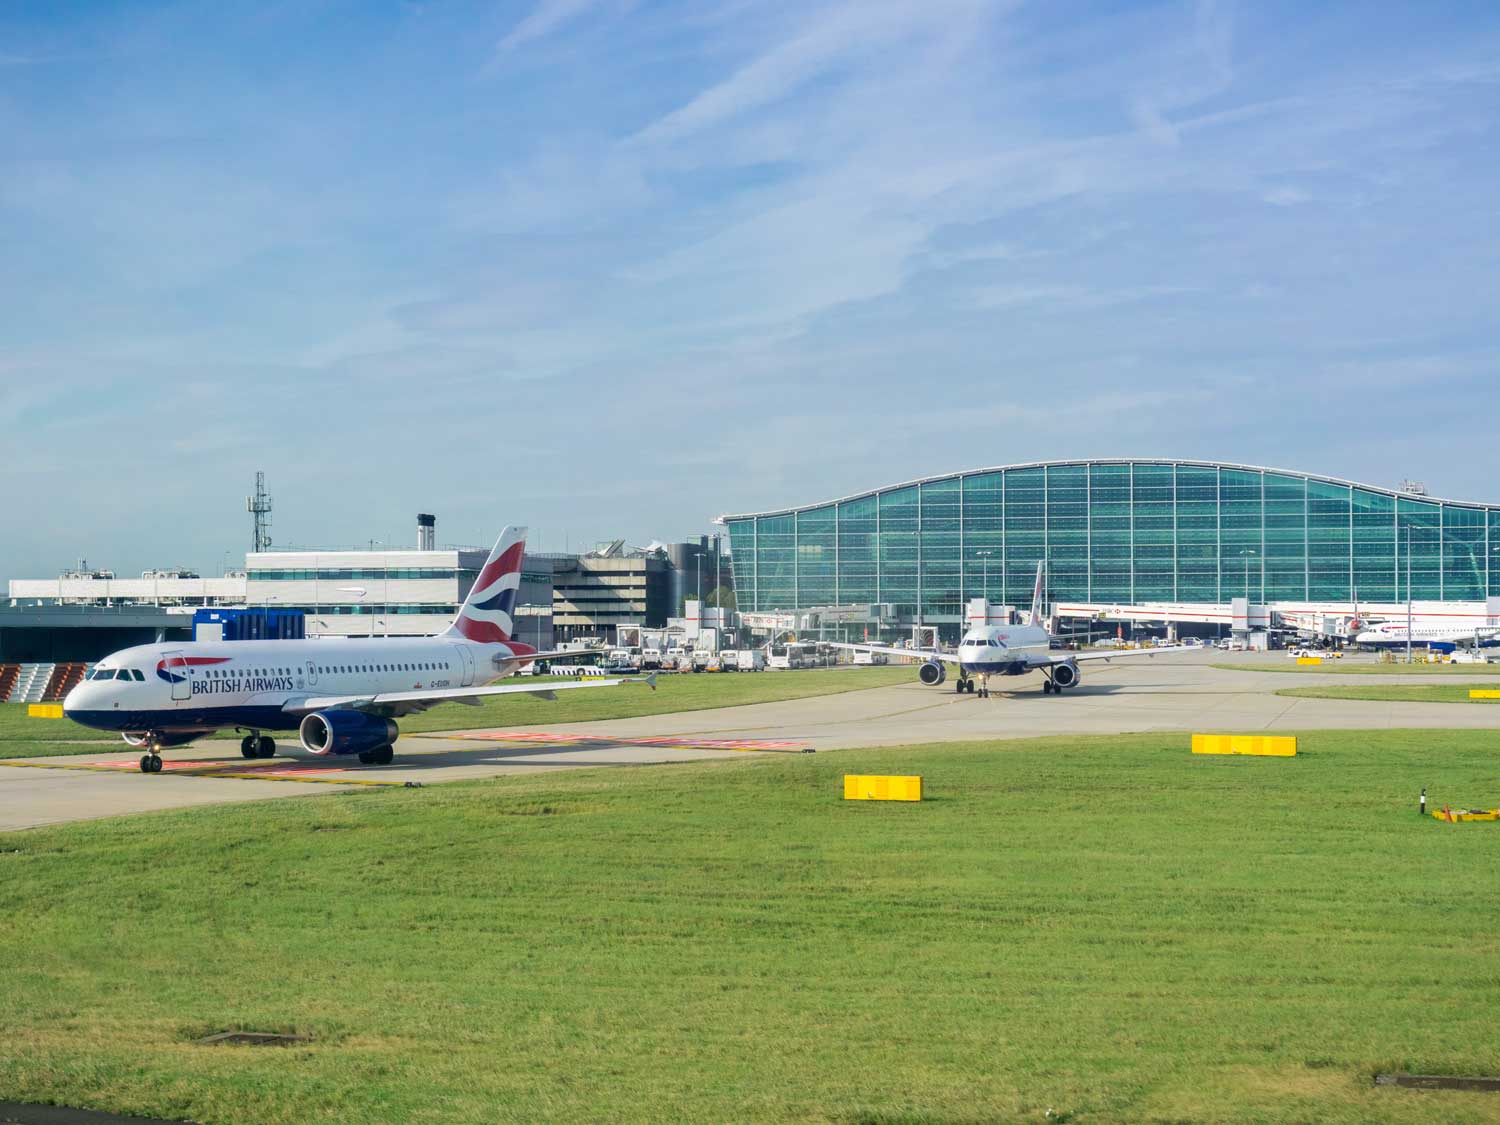
LHR terminal 5

Air freight markets under pressure as capacity struggles to recover

Global air freight markets continue to outperform expectations, but the balance between supply and demand remains fragile. 

What began as a short-term disruption following renewed conflict in the Middle East has evolved into a more structural capacity challenge, keeping rates elevated and limiting available space on key trade lanes.

Although airlines have adapted their networks and capacity is gradually returning, the market has yet to recover the capacity lost earlier this year. At the same time, resilient demand, particularly from the technology sector, continues to absorb available space, leaving shippers facing higher transport costs and reduced flexibility. 

Middle East disruption continues to shape the market

The collapse of the ceasefire between the United States and Iran has extended disruption across international air cargo networks well beyond initial expectations.

Several major international airlines have postponed the planned resumption of passenger and freighter services to the Gulf until at least late October, delaying the return of valuable belly-hold and freighter capacity that traditionally supports Asia-Europe cargo flows.

Before the conflict, around one-third of Asia-Europe air freight transited through Middle Eastern hubs. The loss of those services removed approximately 12% of global air cargo capacity almost overnight, forcing airlines to reroute shipments through alternative gateways and deploy additional direct freighter services wherever possible.

Despite these adjustments, capacity growth has lagged behind demand throughout 2026. Global air cargo demand increased by around 4% during the first half of the year, while available capacity expanded by only around 1%, creating the imbalance that continues to support elevated freight rates.

As a result, industry forecasts have changed significantly. Expectations that freight rates would fall during 2026 have been replaced by forecasts of annual increases up to 15%, reflecting the ongoing supply constraints affecting the market.

Demand remains resilient as market dynamics evolve

While geopolitical disruption has constrained capacity, changing demand patterns are also reshaping global air freight.

The rapid growth of artificial intelligence infrastructure is generating exceptional demand for semiconductor and data centre equipment, particularly on Transpacific services. Global semiconductor sales more than doubled year on year during the spring, creating sustained demand for premium air freight capacity.

Although AI-related shipments still represent a relatively small proportion of total air cargo volumes, they are highly concentrated on key trade lanes and typically require fast, reliable transport, placing additional pressure on available freighter capacity.

By contrast, the extraordinary growth in cross-border e-commerce that has supported air freight markets in recent years is beginning to moderate.

Changes to low-value import rules in both the United States and the European Union have reduced demand for some e-commerce shipments, with exports of low-value goods from China continuing to decline. While this has eased pressure on certain trade lanes, the reduction has been more than offset by continued strength in industrial manufacturing, technology exports and higher-value cargo.

Airlines continue to compete for scarce freighter capacity

The industry's ability to respond to changing demand remains constrained by a shortage of dedicated freighter aircraft.

Delays to new passenger aircraft deliveries continue to limit passenger-to-freighter conversion programmes, restricting the supply of additional cargo aircraft entering the market. As a result, airlines are increasingly competing not only for freight but also for access to aircraft.

Rather than expanding fleets rapidly, many operators are pursuing partnerships, aircraft acquisitions and strategic investments to secure long-term capacity. Others are repositioning aircraft between markets as demand changes, with freighter deployment shifting rapidly between Asia, Europe and the Americas in response to geopolitical events, humanitarian operations and changing trade flows.

This lack of spare capacity means the market remains particularly vulnerable to further disruption. Any significant geopolitical event, weather-related disruption or operational shock has the potential to tighten capacity quickly and place renewed upward pressure on rates.

Planning ahead remains the best strategy

Although capacity is expected to improve gradually during the second half of the year, market conditions remain unpredictable.

For shippers moving time-critical or high-value cargo, securing capacity early, maintaining flexible transport options and working closely with dependable logistics partners will remain essential. Businesses that rely on just-in-time supply chains or seasonal inventory should continue to allow additional planning time while airlines rebuild network resilience.

The market has demonstrated remarkable resilience throughout 2026, but it also highlights how quickly global air freight can be reshaped by geopolitical events, changing technology demand and structural capacity constraints.

Keeping your supply chain moving

When capacity is tight, reliability, experience, network strength and proactive planning make the difference.

Metro works with leading airlines and global carrier partners to secure stable air freight capacity across key international trade lanes. Our experienced teams provide tailored routing solutions, customs expertise and end-to-end shipment management, helping customers minimise disruption and keep critical cargo moving, even in challenging market conditions.

To discuss how Metro can strengthen your global air freight strategy and support your international supply chain, EMAIL Managing Director Andrew Smith today.
Trade handshake

UK trade deals open new opportunities

The UK's trade agenda continues to gather momentum, creating new opportunities for businesses trading internationally, while reshaping the way they access global markets. 

The most recent agreements with major trading partners across Asia-Pacific, the Gulf, North America and Europe have expanded market access, reduced tariffs and strengthened supply chain resilience.

For UK businesses, these agreements represent far more than diplomatic milestones. They offer practical commercial advantages, from lower export costs and simplified market access to stronger supply chains and improved regulatory cooperation. While some negotiations remain ongoing, the overall direction is clear: the UK is building an increasingly diverse portfolio of international trading relationships that extends well beyond traditional European markets. 

UK-EU relations continue to evolve

Although the planned UK-EU summit scheduled for July has been postponed following the change in UK political leadership, negotiations have continued behind the scenes.

Officials are progressing work on the mandatory five-year review of the Trade and Cooperation Agreement (TCA), alongside wider discussions aimed at improving the trading relationship.

Several areas could deliver tangible benefits for businesses. Negotiations on sanitary and phytosanitary (SPS) standards are intended to reduce border checks on food and agricultural exports, while discussions continue around linking UK and EU emissions trading systems, cooperation on electricity infrastructure and broader regulatory alignment.

While no major changes have yet been agreed, businesses trading with Europe should continue to monitor developments, as incremental improvements to customs procedures and border processes could reduce friction for many exporters over the coming months.

CPTPP becomes a reality for UK exporters

One of the most significant developments has been Mexico's ratification of the UK's accession to the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) on 22 June 2026.

With Canada expected to complete implementation in September, UK businesses will soon benefit from preferential access across all twelve CPTPP member economies, creating one of the world's largest free trade areas spanning Asia-Pacific, North America and Latin America.

Collectively, CPTPP countries account for around 15% of global GDP and more than 500 million consumers. For exporters, the agreement opens new opportunities across manufacturing, consumer goods, food and drink, automotive, technology and professional services, while giving businesses greater flexibility to diversify international supply chains beyond traditional markets.

Gulf agreement strengthens access to a fast-growing region

May’s new Free Trade Agreement with the Gulf Cooperation Council (GCC) represents another important step in expanding Britain's global trading relationships.

Covering Bahrain, Kuwait, Oman, Qatar, Saudi Arabia and the United Arab Emirates, the agreement is expected to remove hundreds of millions of pounds in annual tariffs on British exports once fully implemented.

Products including food, beverages and consumer goods are expected to benefit from lower duties, while wider provisions covering digital trade, investment and business mobility should make it easier for UK companies to establish and grow commercial operations throughout the Gulf.

For businesses already trading with the Middle East, the agreement offers greater certainty at a time when the region continues to play an increasingly important role in global logistics and supply chains.

Switzerland opens new opportunities for UK exporters

The UK's latest agreement with Switzerland further expands opportunities for British exporters, particularly across agriculture and food production.

The new Free Trade Agreement removes or reduces tariffs on a wide range of British agricultural exports, including lamb, vegetables, dairy products, beef and sparkling wine, while also strengthening services trade between the two countries.

The agreement, which was finalised on 13 July is expected to increase bilateral trade by more than £7 billion annually, reinforcing Switzerland's importance as one of the UK's highest-value trading partners.

UK-US cooperation goes beyond tariffs

The UK and United States continue to strengthen their trading relationship through pharmaceutical supply chain agreement signed at the end of 2025.

The arrangement protects more than £5 billion of annual UK pharmaceutical exports from tariffs while creating closer cooperation on medicine availability, manufacturing resilience and regulatory alignment.

Beyond the life sciences sector, the agreement demonstrates a growing emphasis on supply chain resilience rather than simply reducing tariffs. Greater cooperation on trusted sourcing, manufacturing capacity and regulatory processes reflects the increasing importance governments are placing on securing critical supply chains in strategically important industries.

Turning opportunity into competitive advantage

Securing a trade agreement is only the first step. Real commercial success depends on understanding customs requirements, managing international logistics and building resilient supply chains capable of supporting long-term growth.

Metro helps businesses take full advantage of emerging global trade opportunities through integrated freight forwarding, customs expertise and end-to-end supply chain management. Whether you're looking at new sourcing options or expanding into Europe, North America, the Gulf or the Asia-Pacific region, our global network and local specialists help simplify international trade while reducing cost, risk and complexity.

To discover how Metro can help your business unlock new international trading opportunities, EMAIL Managing Director Andrew Smith today.
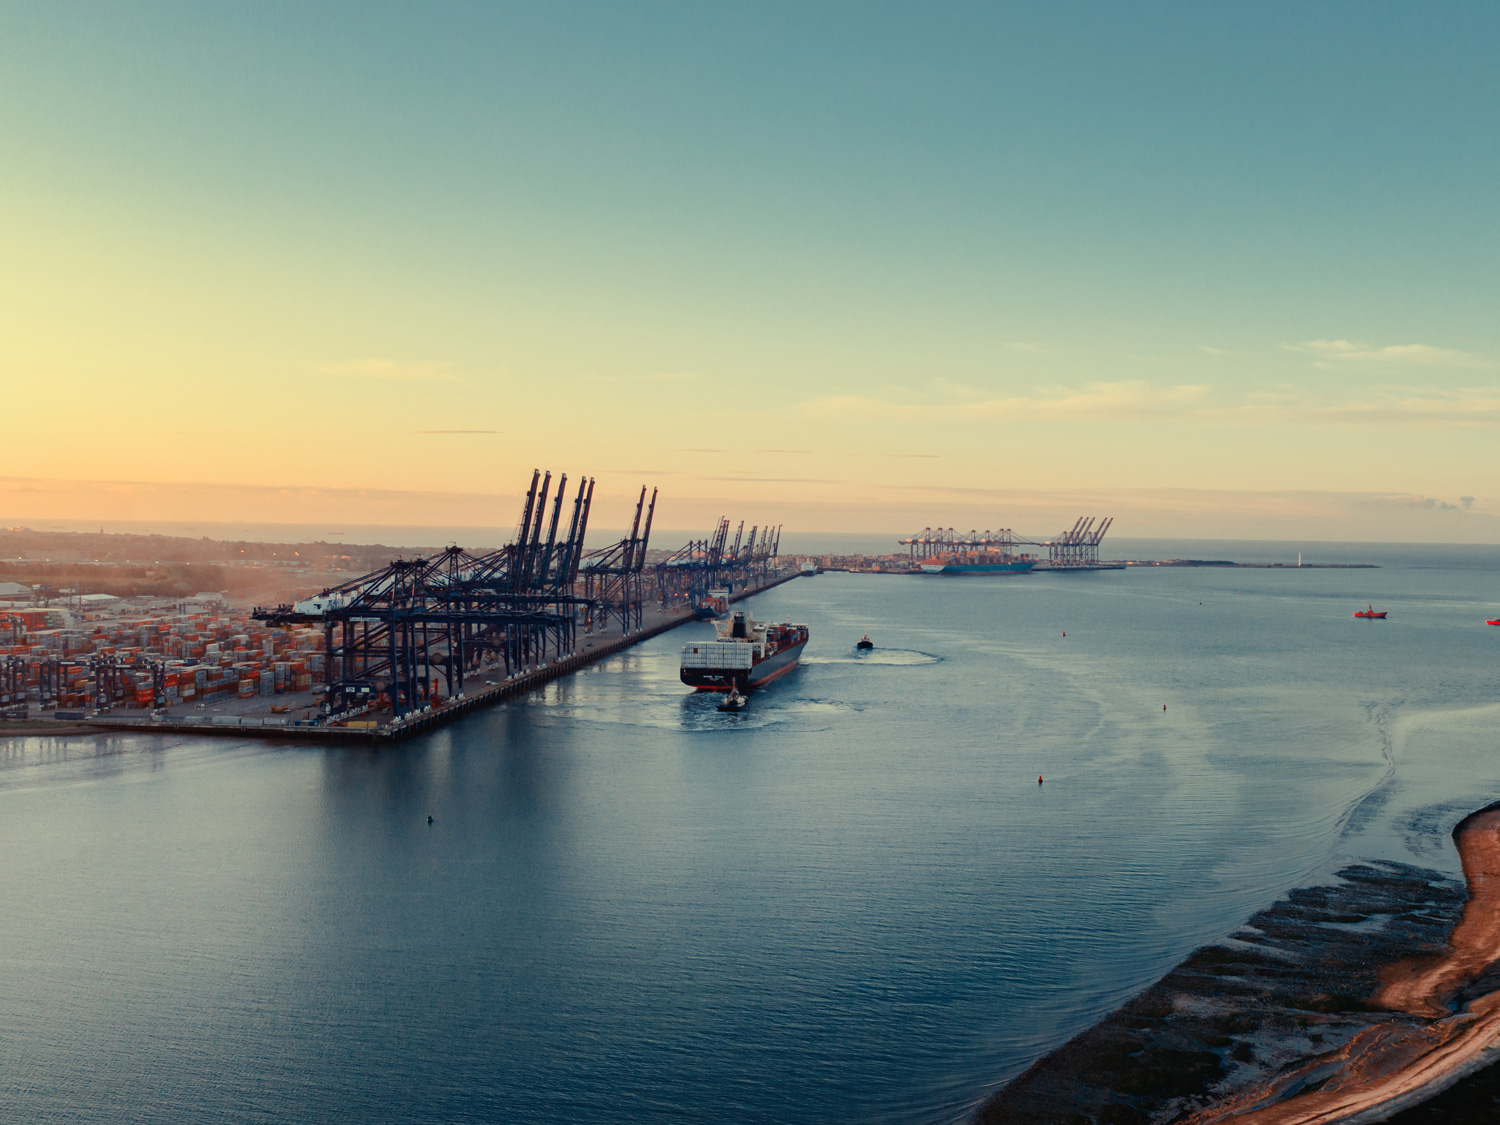
FXT at dawn

Strong demand and constrained capacity are reshaping container shipping

For much of the recent past, freight markets have lurched from one disruption to another. Pandemic recovery, conflict in the Red Sea, tariff uncertainty and conflict in the Middle East have each triggered periods of higher freight rates before conditions gradually eased.

This time, however, the market appears to be changing for different reasons.

While geopolitical events continue to influence global shipping, they are no longer the only force keeping container capacity tight. Strong international trade, sustained investment in new industries and persistent congestion across global transport networks are all helping to support freight rates, suggesting the market may remain firmer than many shippers anticipated.

Global trade continues to absorb available capacity

One of the strongest indicators is that cargo volumes continue to grow despite higher transport costs.

Global container traffic has increased by around 4% year on year, with Asia-Europe volumes rising approximately 12% and Asia-North America around 11%, with indexed rates rising 150% over two quarters.

Growth is also becoming more geographically diverse. Alongside resilient demand from Europe and North America, expanding trade with Africa and Latin America is absorbing additional vessel capacity that might previously have been available elsewhere.

At the same time, the mix of cargo moving through global supply chains is changing.

Rather than retailers replenishing inventories and other traditional sources of demand, increasing volumes are being generated by long-term investment in artificial intelligence infrastructure, data centres, batteries, electric vehicles and renewable energy technologies. These emerging industries will require sustained manufacturing and international transport over many years, creating a more durable source of freight demand than short-term consumer buying cycles.

More ships do not necessarily mean more capacity

Although shipping lines have ordered record numbers of new vessels, effective shipping capacity remains far tighter than headline fleet statistics suggest.

Only around 2% of the global container fleet is currently idle, while demand for charter vessels (particularly ships above 3,000 TEU) continues to strengthen. Carrier profitability also recovered sharply during the second quarter, reflecting healthier trading conditions after a difficult start to the year.

Meanwhile, operational constraints continue to reduce available capacity.

Most container services remain diverted around the Cape of Good Hope instead of using the Red Sea, significantly extending voyage times. Transit through the Strait of Hormuz remains uncertain following renewed regional tensions, while congestion at several major ports continues to delay vessel turnaround times.

Together, these factors mean carriers are deploying almost every available ship simply to maintain existing service networks.

Air freight points to the same underlying trend

Container shipping is not the only transport mode experiencing stronger market conditions.

Air freight demand has also continued to strengthen since the second quarter, despite improving airline capacity and fewer operational disruptions, driving indexed rates up by a quarter in under six months.

When both ocean and air freight markets strengthen simultaneously, it indicates that demand for international transport is expanding across global supply chains rather than being driven solely by disruption affecting one particular trade route.

For cargo owners, that provides further evidence that today's freight market reflects broader structural demand rather than temporary geopolitical events alone.

Peak season is likely to remain challenging

Looking ahead, while some softening is probably inevitable, there is little indication that market conditions will change significantly before the end of the year.

Strong demand, limited spare shipping capacity, continuing port congestion and ongoing geopolitical uncertainty are all expected to support freight rates throughout the traditional peak season.

While some carriers have begun limited returns through the Suez Canal, these remain selective and do not yet represent a wider restoration of normal operating patterns.

As a result, businesses should continue planning for constrained capacity, longer booking lead times and freight costs remaining above historical averages.

Relief is coming, but not immediately

The substantial order-book of new container ships scheduled for delivery during 2027 and 2028 should eventually restore greater balance between supply and demand.

Until then, however, the combination of resilient trade growth and restricted effective capacity is likely to keep freight markets tighter than many expected earlier this year.

Rather than waiting for rates to fall, businesses should continue reviewing freight budgets, securing capacity early and building flexibility into their supply chain planning to reduce exposure to market volatility.

Metro can help you stay ahead of changing market conditions

Freight markets are evolving rapidly, making forward planning more important than ever. Whether you're reviewing sourcing strategies, managing peak season demand or looking to reduce transport costs through smarter routing and capacity planning, Metro's ocean freight specialists can help.

With global carrier relationships, flexible routing options and tailored supply chain solutions, we work alongside customers to secure reliable capacity and build resilient logistics strategies that keep cargo moving, whatever the market conditions. 

EMAIL Metro’s Managing Director, Andrew Smith to discuss how we can support your international supply chain.

RoRo PCC

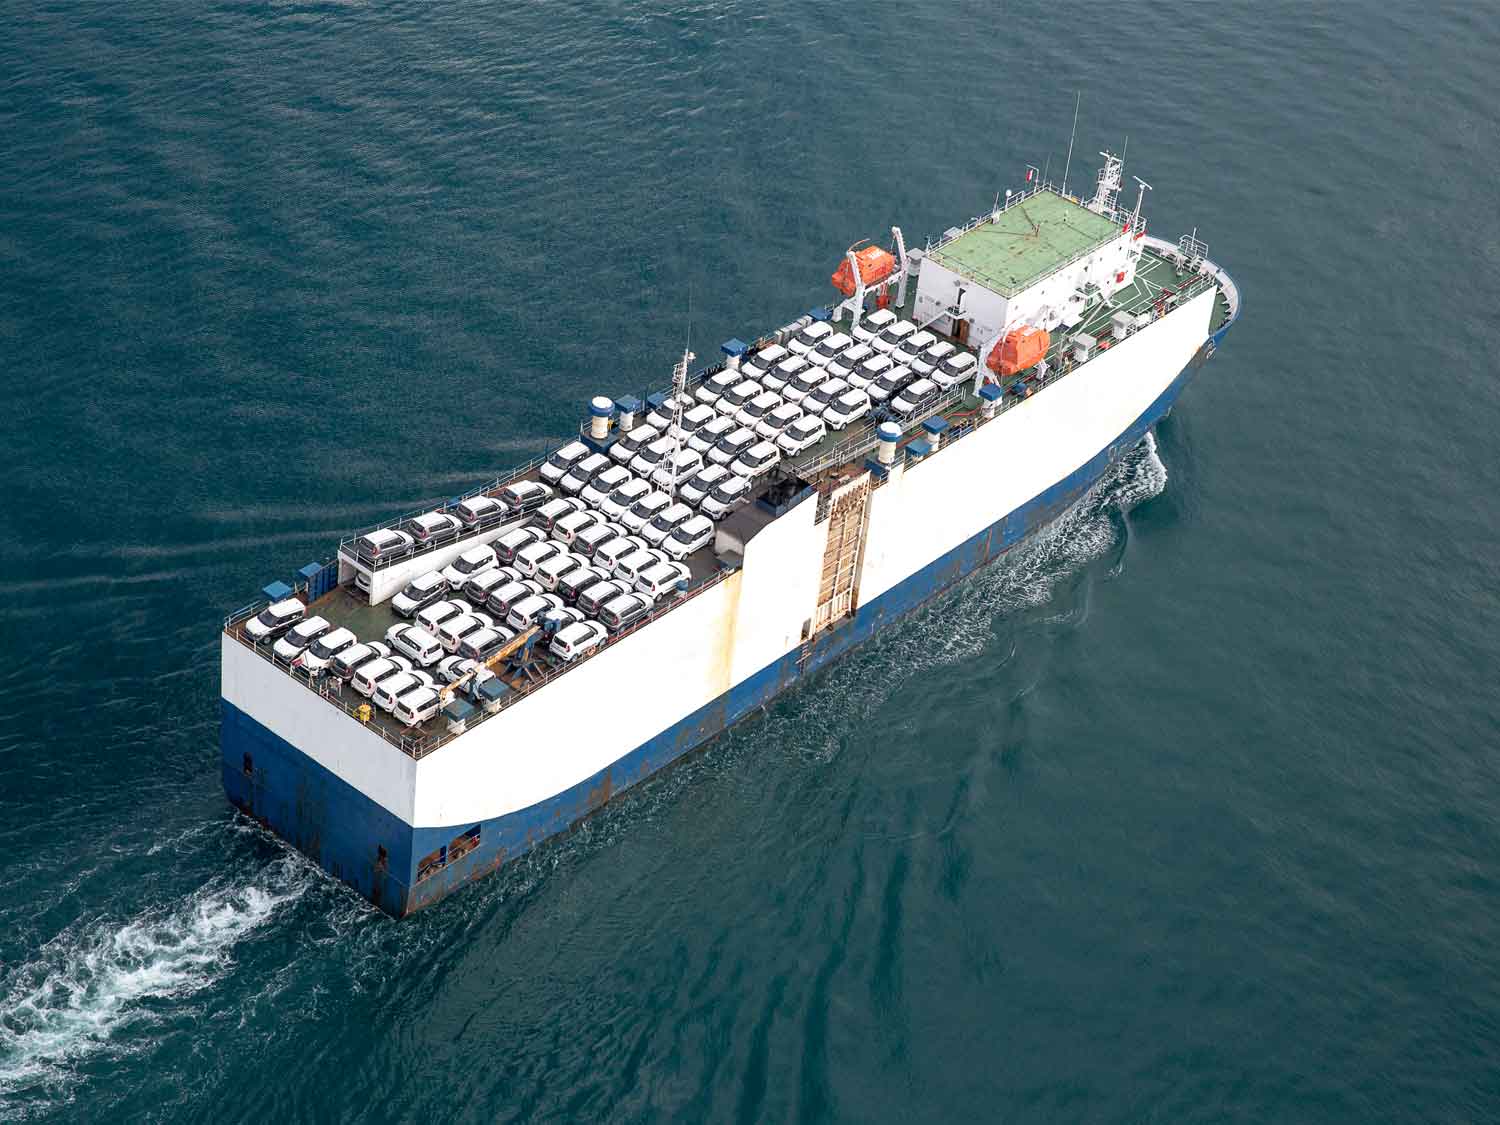
A new era for the global RoRo fleet

It wasn't long ago that securing space on a RoRo vehicle carrier was one of the biggest challenges facing automotive manufacturers. A shortage of Pure Car and Truck Carriers (PCTCs), soaring charter rates and surging Chinese vehicle exports created an exceptionally tight global market.

That picture is beginning to change. A significant wave of new vessel deliveries is increasing global capacity, charter rates are easing and vehicle production is becoming more regionalised as Chinese manufacturers establish factories closer to overseas markets.

For manufacturers, the challenge is no longer simply securing vessel space. Understanding how changing trade flows, regional production and evolving carrier networks affect future supply chains will be just as important.

Fleet expansion is reshaping capacity

The global PCTC fleet is undergoing its largest expansion for many years. New generations of car carriers, many capable of transporting more than 9,000 car equivalent units, are entering service with dual-fuel propulsion and future-ready designs that support lower-emission operations. 

Overall fleet capacity is expected to increase by around 40%, fundamentally changing the supply-demand balance that drove record charter rates during 2023 and 2024.

As additional vessels enter service, daily charter costs have fallen significantly from their historic highs, easing some of the pressure that has affected vehicle exporters over the past two years.

For automotive manufacturers, this represents a welcome improvement in available capacity, although freight markets remain far from returning to pre-disruption conditions.

Competition is intensifying

China's vehicle exports have surged by more than 60% this year, with Europe emerging as one of its fastest-growing overseas markets. Chinese brands continue to gain market share, particularly in the UK and parts of Southern and Eastern Europe.

However, the next phase of expansion is unlikely to rely solely on long-haul exports.

Faced with higher import tariffs in Europe and North America, Chinese automotive manufacturers are accelerating investment in overseas production. New assembly plants are being established across Europe, South America, Southeast Asia, India and South Africa, allowing vehicles to be built closer to customers while reducing tariff exposure.

For the RoRo sector, this creates a dual dynamic. Long-haul exports from China are expected to moderate over time as production shifts closer to end markets, while regional and short-sea vehicle movements within Europe are likely to grow as new production facilities come online. Investment in new European short-sea vehicle carriers already reflects these changing trade patterns.

Additional investment supports employment, strengthens regional supply chains and creates greater demand for automotive logistics across the continent. At the same time, European manufacturers face increasing competition, making resilient and efficient supply chains even more important.

Project cargo remains under pressure

While finished vehicle logistics should benefit from the expanding fleet, the outlook is less positive for project cargo and other high and heavy freight.

Construction equipment, agricultural machinery, industrial vehicles and oversized project cargo continue to compete for limited specialist deck space. The newest PCTCs are optimised for passenger vehicles rather than abnormal loads, meaning stowage flexibility for oversized freight remains constrained despite overall fleet growth.

Meanwhile, longer voyages around the Cape of Good Hope continue to absorb vessel capacity following disruption in the Red Sea, while higher bunker costs and operating expenses are maintaining commercial pressure on older and smaller RoRo vessels.

For shippers moving specialist equipment, early planning and close coordination with carriers remain essential to securing both space and suitable stowage.

Automotive supply chains need greater agility

The RoRo market is becoming more balanced, but not necessarily simpler. Vehicle production is becoming increasingly regional, trade routes are evolving, environmental regulations continue to influence fleet investment and geopolitical developments remain capable of reshaping shipping patterns with little warning.

For UK and European automotive manufacturers, success will increasingly depend on logistics partners that understand both global vehicle flows and local manufacturing requirements, helping them respond quickly as sourcing patterns and transport networks continue to evolve.

Drive resilience with Metro

Metro has extensive experience supporting OEMs, Tier 1 suppliers and automotive manufacturers with integrated international logistics solutions. 

Our specialist automotive teams work across Europe, Asia and North America to secure RoRo capacity, manage complex vehicle movements and develop contingency plans when market conditions change.

Whether moving finished vehicles, production components or specialist project cargo, Metro combines global carrier relationships with local expertise to keep automotive supply chains moving efficiently and reliably.

To discuss your automotive logistics requirements and discover how Metro can strengthen your supply chain, EMAIL Andrew Smith, Managing Director.