graph rising

Early peak season continues to support higher ocean rates

Peak season arrived earlier than expected this year, but it shows little sign of easing. Ocean freight rates from Asia to Europe continue to climb as strong demand, disciplined capacity management and lingering geopolitical uncertainty combine to keep pressure on both pricing and vessel space.

The latest round of carrier price increases introduced at the start of July has pushed freight rates higher once again across the Asia-Europe trade. Spot rates have risen by around 7% into North Europe and approximately 10% into the Mediterranean over the past week, extending a market that has steadily strengthened. 

Carriers have maintained tight capacity discipline despite stronger demand, with only a handful of blank sailings currently scheduled, suggesting carriers are successfully filling available vessel space rather than artificially restricting capacity. At the same time, higher freight costs linked to ongoing geopolitical disruption continue to support firmer market conditions. 

Middle East uncertainty continues

Although commercial shipping has resumed through the Strait of Hormuz following the recent ceasefire agreement, the market remains cautious.

Security concerns persist across the wider region and operators continue to factor geopolitical risk into network planning and pricing. Cargo flows are gradually normalising, but the disruption has altered routing decisions and placed additional demand on Mediterranean services, where pricing has risen significantly faster than into Northern Europe. 

Historically, Mediterranean services have commanded a modest premium over North Europe due to vessel deployment patterns. Today, however, that pricing gap has widened to levels rarely seen outside the exceptional supply chain disruption experienced during 2022, reflecting the continuing impact of Middle East instability on European trade lanes. 

The market may be approaching its peak

Demand remains healthy rather than accelerating, vessel space is becoming easier to secure on some services and several carriers have started extending rate validity beyond weekly announcements, suggesting they are becoming more confident about short-term pricing. 

However, this should not be mistaken for a return to normal market conditions.

Large volumes of cargo delayed during June still need to move through the network, while carriers continue to manage allocations carefully. Even if freight rates begin to soften later in the summer, they are expected to remain well above the levels seen earlier this year. 

Carrier confidence remains high

Confidence among ocean carriers is also evident in the charter market.

Improving freight earnings have encouraged more shipping lines to secure additional vessel capacity well into 2027 through longer-term charter agreements rather than relying solely on new-build programmes. Demand for available vessels remains strong across several ship sizes, while rising charter values and vessel prices underline continued 

confidence that freight markets will remain relatively firm for some time. 

For shippers, the message remains unchanged. The current market is being driven by resilient demand, disciplined carrier capacity management and ongoing geopolitical uncertainty rather than short-term disruption alone. Businesses leaving bookings until the last minute are likely to face reduced flexibility, higher costs and fewer routing options.

Plan ahead with Metro

Securing capacity early has become just as important as negotiating freight rates. Metro's ocean freight specialists continuously monitor carrier capacity, market conditions and routing options to help customers minimise disruption and manage transport costs in a fast-changing market.

To discuss your Asia-Europe shipping requirements and build greater resilience into your supply chain, EMAIL our managing director Andrew Smith.
Emirates Dubai

Air freight remains resilient despite Middle East tensions

Global cargo volumes remained strong throughout June, finishing 9% higher than the same month last year and building on steady growth seen throughout the first half of 2026. 

While capacity has gradually returned to the market following the disruption caused by the Iran-US conflict, pricing remains significantly above last year's levels as airlines continue to operate in a more complex and uncertain environment. 

Although the ceasefire had allowed airlines to restore many services across the Gulf, it is proving to be very fragile and the market is far from returning to normal.

The European Union Aviation Safety Agency on 7 July extended guidance advising airlines to avoid Iranian, Iraqi and Lebanese airspace until the end of August following renewed exchanges between the US and Iran. While restrictions affecting several Gulf states have been relaxed, airlines operating between Europe and Asia continue to face longer routings around conflict zones, increasing both flight times and operating costs. 

Many Gulf carriers have rebuilt schedules and returned aircraft to service, helping overall capacity recover. However, operational planning remains heavily influenced by evolving security assessments, insurance requirements and regulatory guidance, meaning disruption can quickly return if regional tensions escalate. 

Capacity is improving but rates remain elevated

Global air freight capacity has increased by around 3% over recent weeks, with Middle East capacity now marginally above the same period last year. Despite this recovery, average freight rates during June remained approximately one-third higher than a year earlier, underlining how the market continues to price in operational risk as well as strong underlying demand. 

Rates into the Middle East remain particularly elevated compared with pre-conflict levels, although they have eased from the exceptional highs seen during the height of the disruption as more capacity returns to affected trade lanes. 

AI is replacing eCommerce as the growth engine

For several years, cross-border eCommerce drove much of the growth in global air cargo. Today, semiconductor manufacturing, AI infrastructure and high-value technology products have become the primary drivers of demand.

Strong exports from Taiwan and South Korea continue to generate significant volumes across global air freight networks, helping offset weaker eCommerce activity following changes to low-value import rules in both the US and Europe. Overall, air cargo demand continues to outperform expectations despite these changing market dynamics. 

New regulations are reshaping eCommerce

The European Union has now removed de minimus duty-free treatment for low-value imports, introducing additional customs charges on individual shipments from outside the bloc. The immediate result has been a sharp reduction in direct freighter capacity between China and Europe as eCommerce operators assess the commercial impact and adapt their distribution strategies.

While experience in the US suggests volumes are likely to recover over time, many businesses are expected to shift towards larger consolidated consignments rather than individual parcel movements, changing the mix of cargo moving through international air freight networks. 

While capacity is gradually returning and some pricing pressures have eased, the combination of geopolitical risk, regulatory change and evolving demand means air freight remains a market where agility and forward planning continue to deliver a competitive advantage.

Metro's air freight specialists monitor market developments daily, helping customers secure reliable capacity, identify the most effective routings and respond quickly as conditions evolve.

To discuss your international air freight requirements and build greater resilience into your supply chain, EMAIL Andrew Smith, Metro’s Managing Director.

RoRo PCC

A new era for the global RoRo fleet

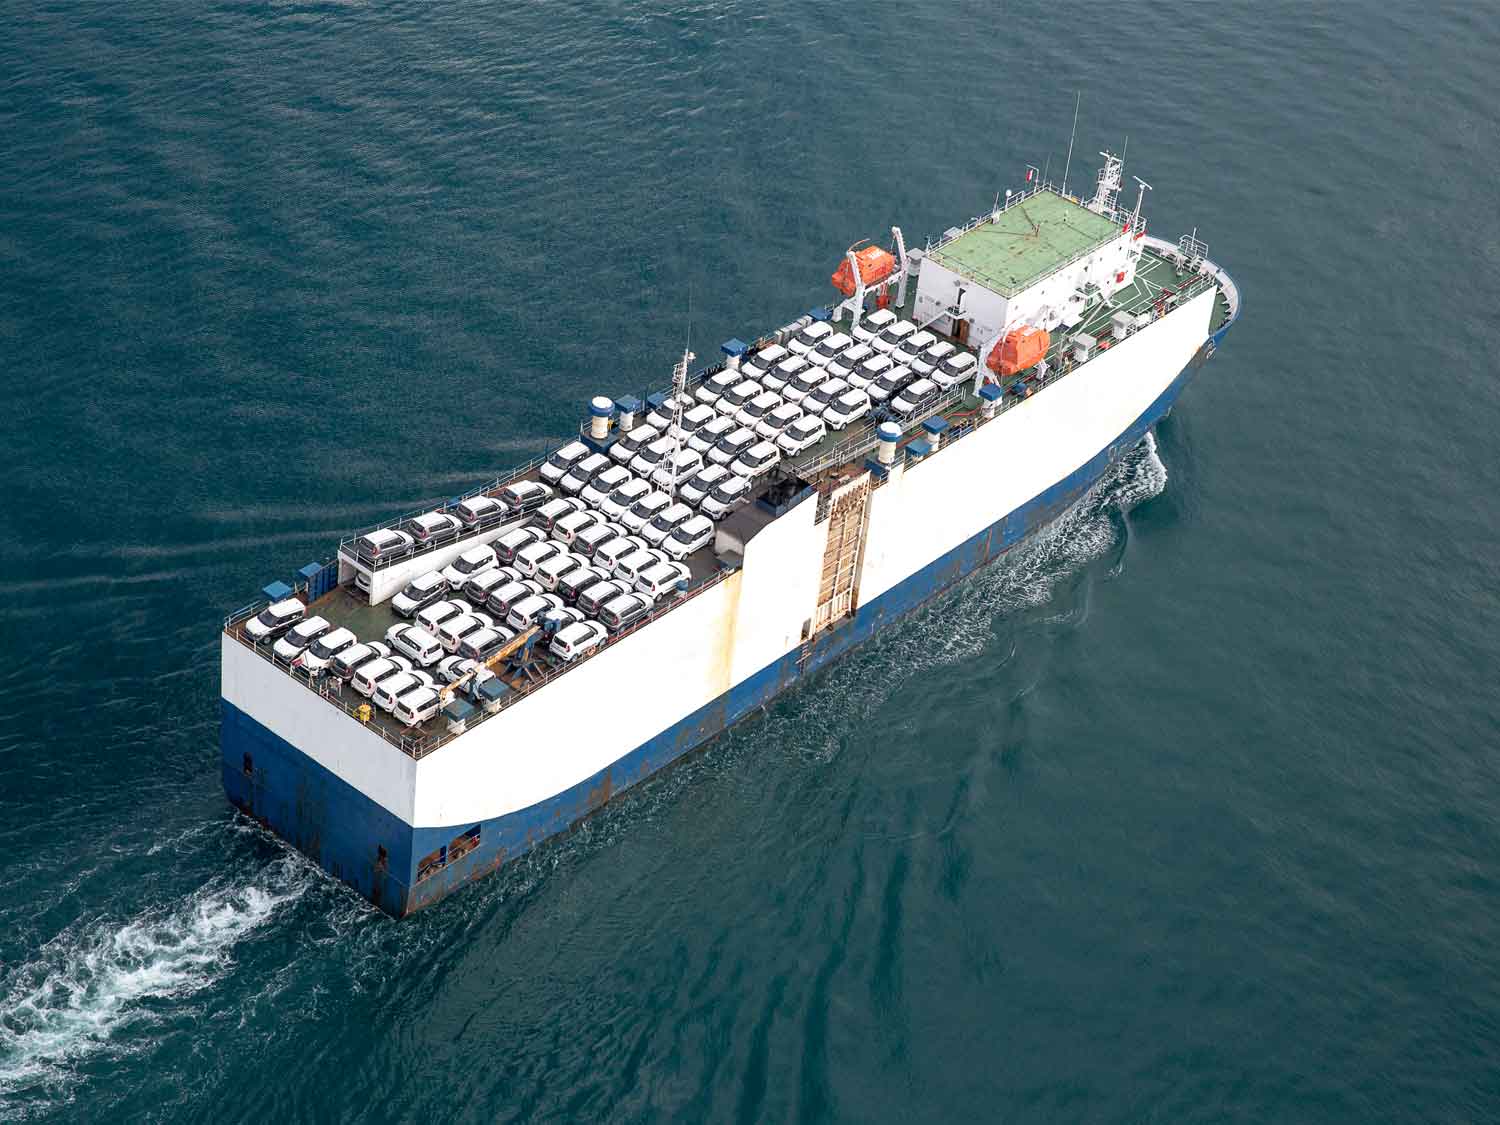
It wasn't long ago that securing space on a RoRo vehicle carrier was one of the biggest challenges facing automotive manufacturers. A shortage of Pure Car and Truck Carriers (PCTCs), soaring charter rates and surging Chinese vehicle exports created an exceptionally tight global market.

That picture is beginning to change. A significant wave of new vessel deliveries is increasing global capacity, charter rates are easing and vehicle production is becoming more regionalised as Chinese manufacturers establish factories closer to overseas markets.

For manufacturers, the challenge is no longer simply securing vessel space. Understanding how changing trade flows, regional production and evolving carrier networks affect future supply chains will be just as important.

Fleet expansion is reshaping capacity

The global PCTC fleet is undergoing its largest expansion for many years. New generations of car carriers, many capable of transporting more than 9,000 car equivalent units, are entering service with dual-fuel propulsion and future-ready designs that support lower-emission operations. 

Overall fleet capacity is expected to increase by around 40%, fundamentally changing the supply-demand balance that drove record charter rates during 2023 and 2024.

As additional vessels enter service, daily charter costs have fallen significantly from their historic highs, easing some of the pressure that has affected vehicle exporters over the past two years.

For automotive manufacturers, this represents a welcome improvement in available capacity, although freight markets remain far from returning to pre-disruption conditions.

Competition is intensifying

China's vehicle exports have surged by more than 60% this year, with Europe emerging as one of its fastest-growing overseas markets. Chinese brands continue to gain market share, particularly in the UK and parts of Southern and Eastern Europe.

However, the next phase of expansion is unlikely to rely solely on long-haul exports.

Faced with higher import tariffs in Europe and North America, Chinese automotive manufacturers are accelerating investment in overseas production. New assembly plants are being established across Europe, South America, Southeast Asia, India and South Africa, allowing vehicles to be built closer to customers while reducing tariff exposure.

For the RoRo sector, this creates a dual dynamic. Long-haul exports from China are expected to moderate over time as production shifts closer to end markets, while regional and short-sea vehicle movements within Europe are likely to grow as new production facilities come online. Investment in new European short-sea vehicle carriers already reflects these changing trade patterns.

Additional investment supports employment, strengthens regional supply chains and creates greater demand for automotive logistics across the continent. At the same time, European manufacturers face increasing competition, making resilient and efficient supply chains even more important.

Project cargo remains under pressure

While finished vehicle logistics should benefit from the expanding fleet, the outlook is less positive for project cargo and other high and heavy freight.

Construction equipment, agricultural machinery, industrial vehicles and oversized project cargo continue to compete for limited specialist deck space. The newest PCTCs are optimised for passenger vehicles rather than abnormal loads, meaning stowage flexibility for oversized freight remains constrained despite overall fleet growth.

Meanwhile, longer voyages around the Cape of Good Hope continue to absorb vessel capacity following disruption in the Red Sea, while higher bunker costs and operating expenses are maintaining commercial pressure on older and smaller RoRo vessels.

For shippers moving specialist equipment, early planning and close coordination with carriers remain essential to securing both space and suitable stowage.

Automotive supply chains need greater agility

The RoRo market is becoming more balanced, but not necessarily simpler. Vehicle production is becoming increasingly regional, trade routes are evolving, environmental regulations continue to influence fleet investment and geopolitical developments remain capable of reshaping shipping patterns with little warning.

For UK and European automotive manufacturers, success will increasingly depend on logistics partners that understand both global vehicle flows and local manufacturing requirements, helping them respond quickly as sourcing patterns and transport networks continue to evolve.

Drive resilience with Metro

Metro has extensive experience supporting OEMs, Tier 1 suppliers and automotive manufacturers with integrated international logistics solutions. 

Our specialist automotive teams work across Europe, Asia and North America to secure RoRo capacity, manage complex vehicle movements and develop contingency plans when market conditions change.

Whether moving finished vehicles, production components or specialist project cargo, Metro combines global carrier relationships with local expertise to keep automotive supply chains moving efficiently and reliably.

To discuss your automotive logistics requirements and discover how Metro can strengthen your supply chain, EMAIL Andrew Smith, Managing Director.

India flag on container doors 1440x1080 1

India, the hottest shipping lane

Ocean freight from India has entered a period of intense demand, with tightening vessel space, rising freight rates and increasing competition for capacity across both European and North American trade lanes.

For businesses diversifying manufacturing away from China or expanding sourcing across South Asia, the challenge is no longer finding suppliers. It is securing reliable shipping capacity in an increasingly constrained market.

Capacity constraints are driving the market

The India-Europe trade has tightened significantly over recent weeks as booming export demand collides with reduced vessel availability.

While demand has recovered strongly, carriers have removed a substantial amount of capacity through blank sailings, cancelled departures, port omissions and revised service schedules. Between March and early July, more than one in five scheduled sailings between India and Europe failed to operate, reducing overall capacity by around 17% across the trade.

The result has been widespread vessel overbooking, booking windows stretching to four to six weeks, and an increasing risk of cargo either being rolled or, in some cases, having confirmed bookings cancelled and rebooked onto later sailings.

Freight rates have responded accordingly. Average pricing from western Indian gateways into Northern Europe has increased by up to 50% in little more than a month, with further peak season surcharges already announced for the second half of July.

Rather than being driven by a single disruption, the current market reflects a genuine supply and demand imbalance, with available vessel space struggling to keep pace with export demand.

Service reliability is becoming just as important as capacity

The tightening market is being compounded by inconsistent service performance.

Several India-Europe services have experienced repeated blank sailings over recent months, while others have omitted key North European ports, further reducing effective capacity available to shippers. On some loops, weekly departures have become considerably less frequent, extending delays whenever cargo is rolled to a subsequent sailing.

At the same time, schedule reliability varies significantly between carrier networks. While some services continue to operate with consistently high reliability through the deployment of additional vessels, others continue to experience frequent disruption and irregular departures.

For shippers, choosing the right carrier and service has become just as important as securing vessel space itself.

Pressure is spreading across South Asia

Across the wider South Asia region, carriers have introduced substantially higher Freight All Kinds (FAK) levels into both North Europe and Mediterranean markets. These increases represent step changes of around 30-50% compared with pricing seen at the end of the first quarter.

These adjustments reflect a broader reset in carrier expectations. With capacity constrained and demand holding firm, pricing is being recalibrated to reflect both operational pressures and ongoing network disruption.

While some variation remains across individual trade lanes, the direction of travel is consistent: a more expensive and less flexible South Asia-Europe market through the current peak season.

US demand is adding further pressure

Demand on the India-US East Coast lane has surged in recent weeks, with booking volumes more than doubling normal levels and freight rates increasing by more than 80% over a four-week period.

In response, one major carrier is preparing to reinstate a previously withdrawn India-US 

East Coast service only weeks after suspending it, underlining how quickly supply and demand dynamics have changed.

This matters for European shippers because carriers continue to allocate vessels where returns are strongest. Strong demand across North American services inevitably competes with India-Europe for finite vessel capacity, making space increasingly valuable across both trades.

Local expertise makes the difference

With an expanding office network across India, Metro’s local teams coordinate factory collections, inland movements, port operations and ocean bookings as a single integrated flow, providing customers with earlier visibility of capacity constraints and greater flexibility when market conditions change.

Whether that means using alternative gateways, splitting shipments across multiple sailings or combining ocean freight with targeted air solutions for time-critical cargo, we help businesses maintain continuity while controlling transport costs.

To discuss your India-Europe or India-North America shipping requirements, EMAIL Metro’s Managing Director.