Mundra Port

Container trade stays strong as disruption reshapes east–west markets

Global container trade is proving remarkably resilient, but record volumes mask a more complicated picture across the major east–west trades. Congestion, blank sailings and inland constraints are increasingly determining the conditions shippers experience.

July set a new monthly record for global container shipping, with 17.3 million TEU moved worldwide. Volumes were 4.5% higher than July 2025 and are running 5.1% ahead year to date.

That underlying strength matters. Despite geopolitical disruption, changing tariffs and widespread port delays, international containerised trade continues to grow.

But demand alone does not explain current freight conditions. Carrier capacity management, severe congestion at Asian ports and pressure on destination transport networks are creating increasingly different conditions by trade lane.

East–west markets move apart

The clearest divergence is between Asia–Europe and the transpacific.

Asia–Europe spot rates have continued to soften, with Shanghai–Rotterdam falling another 2% and Shanghai–Genoa 3% in the latest weekly data. The traditional peak appears to have passed, although congestion and blank sailings are preventing a more rapid correction.

Across the Pacific, the picture is very different. Transpacific demand strengthened as the US peak season extended later than initially expected, with west coast volumes rising 9% week on week in early September and east coast volumes increasing 3%.

Rates have consequently remained firm. Shanghai–Los Angeles increased another 2% in the latest week and Shanghai–New York 1%, following larger gains the previous week.

However, demand is only part of the explanation. Carriers are becoming increasingly active in managing available space through blank sailings, vessel rotations and capacity deployment as China’s Golden Week approaches.

Across the major east–west trades, around 11% of scheduled sailings between mid-September and mid-October are currently expected to be cancelled. More than half of those cancellations are concentrated on the eastbound transpacific, with a further third affecting Asia–North Europe and Mediterranean services.

The pace of change is significant. Announced blank sailings for the four weeks leading into Golden Week jumped almost 56% in just one week, and further cancellations remain possible as carriers adjust networks around the Chinese holiday.

The overall level remains manageable, with almost nine in ten scheduled sailings still expected to operate. But the acceleration in cancellations points to a more active phase of capacity management.

For shippers, softer demand will therefore not necessarily translate directly into lower rates or easier access to space. How aggressively carriers remove capacity before Golden Week and how quickly demand returns afterwards could determine the balance between available space and pricing through October.

Congestion is moving through the network

Capacity management is only one part of the east–west picture. Four successive typhoons have left major Chinese ports working through substantial backlogs.

Between early July and late August, almost 5.8 million TEU of vessel capacity arrived more than seven days late at Chinese ports, which is around three times the level recorded before the storms.

The impact on schedule reliability has been dramatic. According to figures from Sea-Intelligence, global reliability fell over 6% in July to 56.4%, its sharpest monthly deterioration in more than five years, while late vessels were arriving an average of over six days behind schedule.

Conditions became particularly challenging on east–west services during the typhoon period. Asia–Europe on-time performance fell to around 10%, while Asia–North America dropped to 23%.

Although congestion is gradually easing, the network has yet to recover fully. The combination of existing backlogs, the pre-Golden Week export push and subsequent factory closures could prolong disruption into October, with bunched vessel arrivals then feeding through to European and North American ports.

That is particularly relevant in the US, where pressure is already building beyond the quayside.

The National Drayage Spot Market Index is 8.2% higher year on year as driver availability, equipment constraints, terminal turn times and appointment availability tighten the market.

Import containers are waiting six to seven days on average for inland transport at some locations and up to 14 days at individual terminals. Pressure has been reported around Los Angeles/Long Beach, Houston, Chicago, Memphis, Savannah and other inland gateways.

For US importers, securing ocean space is therefore only one part of the challenge. Drayage and inland capacity need to be planned earlier, particularly when disrupted schedules result in several vessels and large volumes of cargo arriving within a compressed period.

India disruption continues beyond Mundra strike

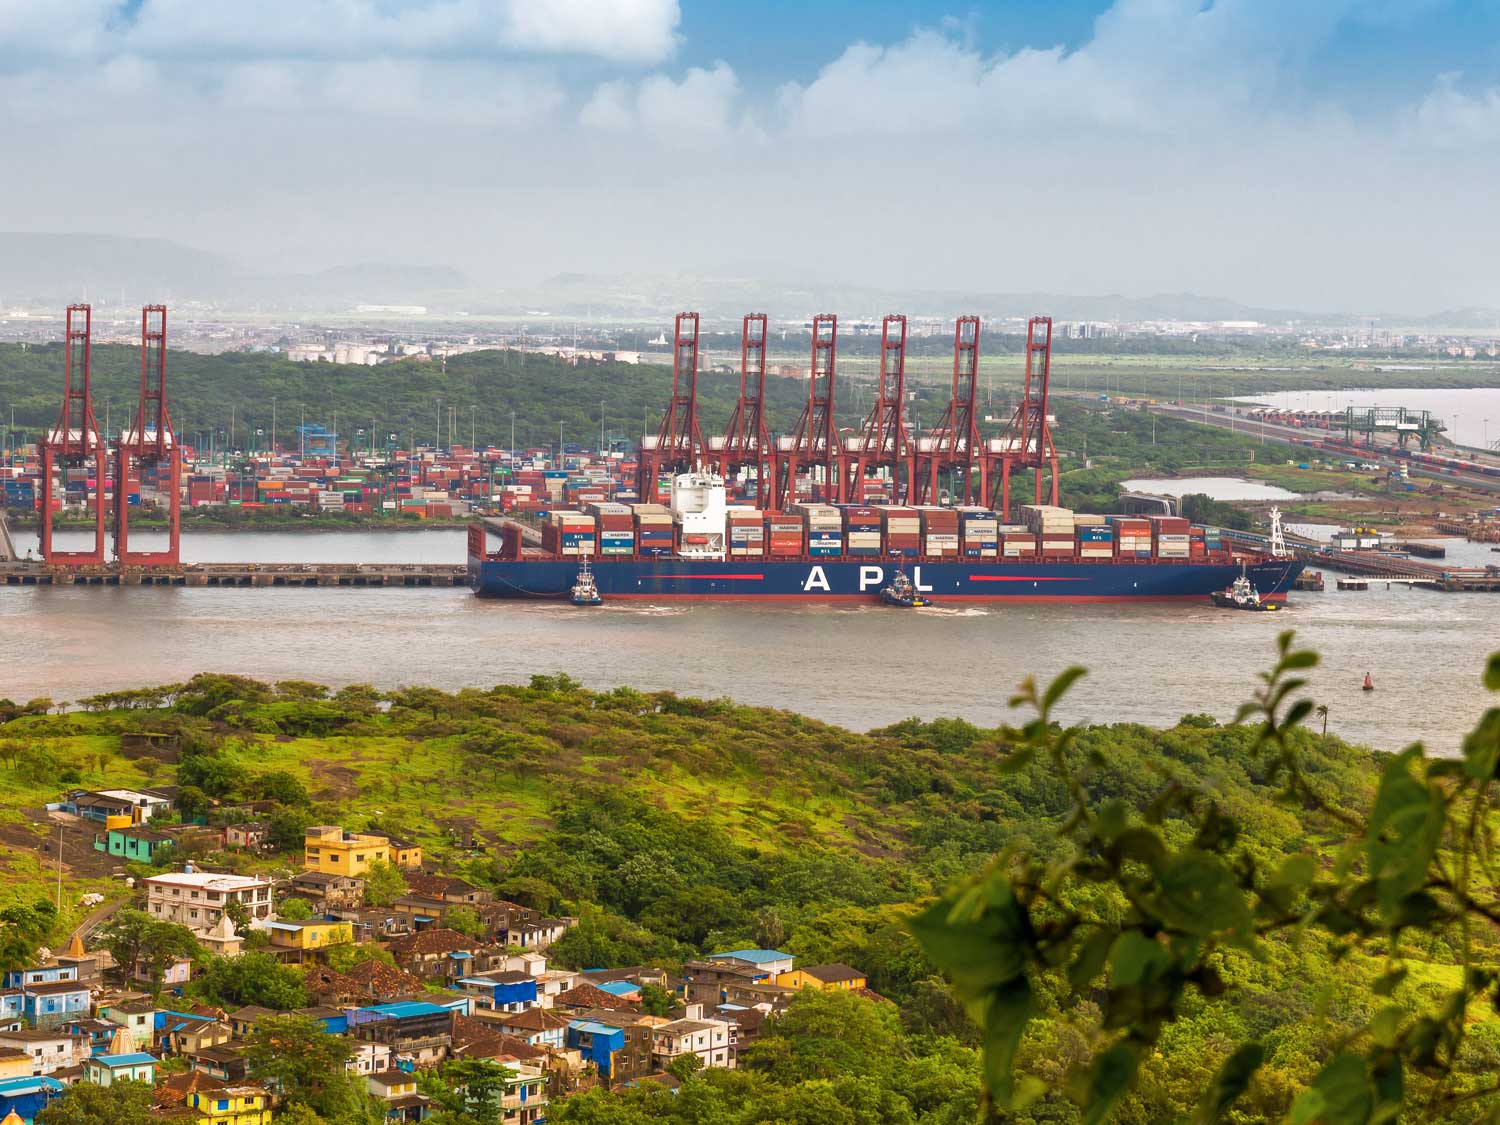
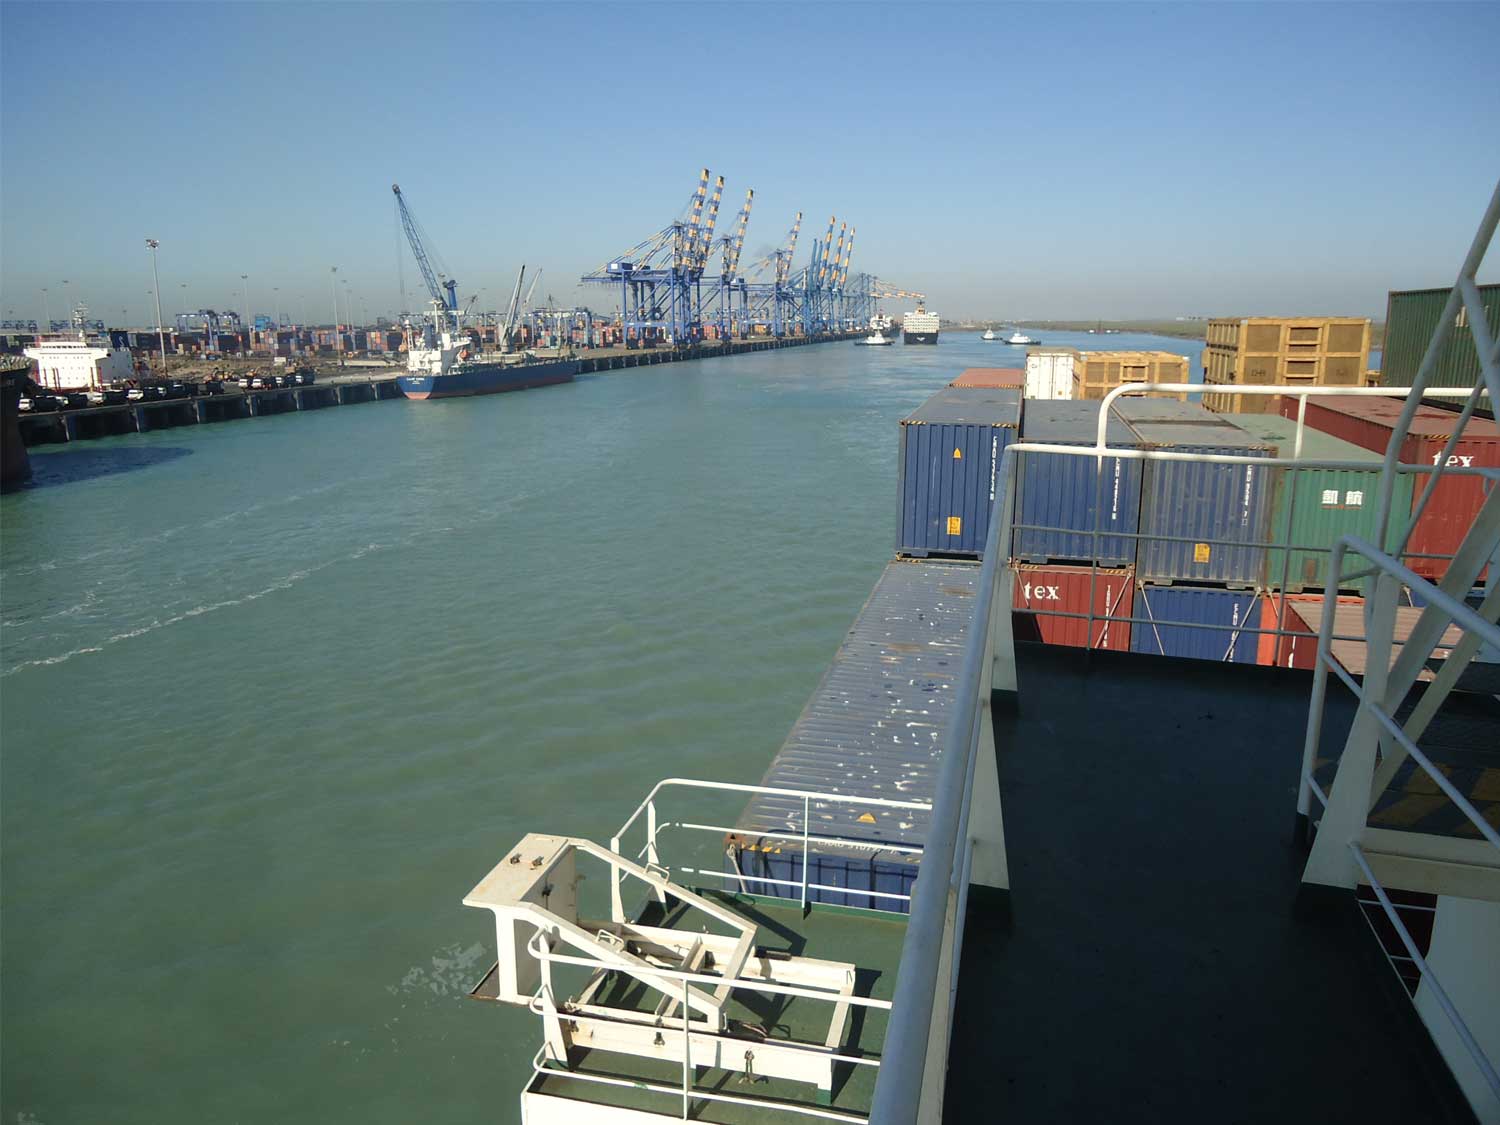
The end of the 13-day dispute affecting empty container yards at Mundra has not brought an immediate return to normal operations.

The strike officially ended on 10 September, but Metro’s team in India continues to report around 5,000 containers delayed each day, with empty container flows particularly affected.

The scale of Mundra makes those continuing delays significant. The port accounts for around 35% of India’s container trade, so disruption can quickly affect equipment availability, exports and wider regional supply chains.

The situation also highlights India’s growing importance within international sourcing strategies as businesses diversify their supply chains and increase manufacturing and procurement activity across the subcontinent.

Metro India continues to scale strategically in response. The business is expanding across seven locations, creating a stronger platform for sourcing, consolidation, origin management and exports across the Indian subcontinent.

Overall, ocean markets remains stronger and more complicated than headline rate movements suggest. Global container volumes are setting records, but where carriers deploy capacity, how quickly Asian ports clear backlogs and whether inland networks can absorb arriving cargo will shape conditions through Golden Week and into October.

We may return to examine these developing themes in more detail, as the impact of Golden Week becomes clearer.

Metro combines global ocean freight buying power with local expertise across key origin and destination markets, including our expanding operation in India and established US network. We monitor capacity, blank sailings, port conditions, equipment availability and inland constraints throughout the journey, giving customers the intelligence and routing options to act before disruption reaches their supply chain.

Image: Adapted from The port of Mundra in Gujarat by Felix Dance, via Wikimedia CommonsCC BY 2.0.

India industrial revolution 1440x1080 1

India’s sourcing growth creates pressure at both ends of the supply chain

UK businesses sourcing from India face rising logistics costs before and after production, as more expensive Asian imports combine with tight westbound capacity and strong India–Europe demand.

India continues to strengthen its position as a manufacturing and sourcing alternative for UK and European businesses. But the cost of moving goods through the supply chains supporting that growth is rising.

The pressure starts well before finished products leave India. Many manufacturers rely on machinery, components, chemicals, electronics and other inputs imported from China and neighbouring Asian markets. Freight costs on those inbound routes have risen sharply, increasing the cost base for Indian production.

At the same time, strong exports are tightening India–Europe container capacity and pushing westbound freight costs higher.

For UK buyers, that creates a potential double freight squeeze, with logistics inflation entering the product cost upstream before another layer is added on the journey to Europe.

Asian imports into India become more expensive

The first pressure point is emerging on eastbound services into India.

During August, Shanghai–Nhava Sheva spot rates have almost doubled compared with July, while Shanghai–Chennai rates have increased by around 60%. Costs from other Asian origins, including Singapore, have also risen significantly.

Strong seasonal imports ahead of India's festival period are contributing to demand, while congestion at major Asian hubs has disrupted schedules and tightened available capacity.

For Indian importers, the impact extends beyond freight rates. Changing schedules and less predictable transit times make it harder to manage inbound inventory and maintain reliable production flows.

Higher freight feeds into manufacturing costs

The significance for UK buyers comes from China's deep integration into Indian manufacturing.

Rising transport costs for the raw materials and components feeding Indian factories may initially be absorbed through manufacturer margins. If elevated costs persist, however, some will inevitably feed into production costs and finished-product pricing.

That creates a supply-chain exposure that may be difficult to see when procurement decisions focus primarily on the factory price.

An Indian-made product can already contain significant logistics costs before it enters a container for its journey to the UK.

Strong exports tighten the westbound market

The second pressure point is India–Europe shipping.

Indian containerised exports to Europe reached an estimated 518,000 TEU during the first half of 2026, with stronger-than-expected demand creating a pronounced capacity squeeze.

Westbound rates increased again during August and are approaching levels last experienced around four years ago. Space has become increasingly difficult to secure, with some leading India–Europe services selling out several weeks ahead and additional spot capacity appearing only as carriers release allocations.

The problem is not simply growing demand. Available capacity has struggled to keep pace.

Blank sailings, congestion and rolled cargo at Nhava Sheva and Mundra are reducing effective space, while some capacity has been redirected towards growing Latin American flows using Indian ports for transhipment.

For cargo owners, guaranteed space can therefore command a premium, while less flexible shipments face greater rollover and delay risks.

Look beyond the supplier price

India's manufacturing scale and expanding trade relationships continue to make it an important sourcing market. But the changing freight environment reinforces the need to assess the complete landed cost of sourcing there.

A product assembled using Chinese or other Asian components may now carry substantially higher inbound logistics costs. Moving the finished goods from India to the UK then adds a second layer of freight inflation.

For lower-margin or freight-intensive products in particular, those combined costs could materially affect sourcing economics.

Timing matters too. With strong westbound bookings and constrained capacity, waiting for cheaper freight could leave importers competing for even tighter space.

Businesses can reduce that exposure by understanding upstream supply flows, consolidating shipments where appropriate and planning westbound capacity earlier.

Manage the whole supply chain, not just the final leg

The growing relationship between Chinese inputs, Indian manufacturing and European demand means these movements cannot always be managed effectively in isolation.

Metro can connect the complete Asia–India–UK supply chain, providing visibility from upstream suppliers through Indian production and onward to the UK. 

With extensive Indian based capabilities, global carrier relationships, consolidation and alternative routing options, we can identify where cost and capacity pressures are building and act before they reach your bottom line. EMAIL Andrew Smith, Metro’s Managing Director, to learn about protecting your landed cost from origin to destination.

Bangladesh label

India and Bangladesh exporters face capacity squeeze

Exporters across India and Bangladesh are facing a difficult combination of strong demand, restricted vessel space, equipment shortages and weather-related disruption, with pressure particularly acute on westbound services to Europe and North America.

Although the underlying causes vary between the two markets, the consequences are similar. Shippers are competing harder for vessel allocations, paying significantly more for available capacity and allowing additional time for cargo to reach its destination.

The situation also illustrates a wider shift in global supply chains. Extreme weather is increasingly interacting with existing capacity constraints, port congestion and geopolitical disruption, turning what might once have been relatively isolated events into much broader operational problems.

Bangladesh loses capacity as carriers prioritise stronger markets

Bangladesh exporters are experiencing a sharp reduction in available ocean capacity as carriers allocate more vessel space and equipment towards China ahead of Golden Week.

One carrier indicated that its Bangladesh booking allocation had fallen from around 2,000 containers to 1,500, a 25% reduction. Equipment is also being repositioned towards China, leaving exporters from Chattogram competing for fewer containers and mother-vessel slots.

Bangladesh is particularly exposed because most exports do not move directly to Europe or North America. Containers typically travel by feeder to hubs including Colombo, Port Klang and Singapore before connecting with larger vessels. When capacity tightens at these transhipment points, Bangladesh allocations can quickly come under pressure.

Continuing Middle East disruption is adding to the problem. Longer vessel rotations around the Cape of Good Hope are absorbing capacity, with Asia–Europe rates reported to be 25% to 40% higher and Asia–US East Coast rates 15% to 25% higher.

For Bangladesh exporters, the increases have been considerably greater. Chattogram–US freight has risen by nearly 130% in a month, while reported pricing to Hamburg has increased by around 140%.

Some shipment bookings are also facing an additional two to three weeks in lead time. Businesses operating under Delivered Duty Paid terms have the greatest immediate financial exposure, although FOB exporters still face the commercial consequences of restricted capacity and delayed deliveries.

Airfreight offers an alternative for urgent cargo, but capacity from Dhaka is also tightening. Europe-bound shipments face particularly strong demand, making early booking and selective use of airfreight increasingly important for protecting critical delivery dates.

India–Europe demand pushes vessel space to a premium

India’s westbound market is experiencing its own capacity squeeze as export demand strengthens faster than available vessel space.

Indian containerised exports to Europe reached an estimated 518,000 TEU during the first half of 2026, while some key carrier services are already fully allocated through August and, on selected sailings, into early September.

Spot freight rates from Nhava Sheva and Mundra to major UK and European gateways have increased by approximately 10% to 15% since late July, reaching their highest levels in around four years. With guaranteed space increasingly valuable, shippers are also facing premiums where they need firm allocations.

Part of the constraint reflects carrier network decisions, including the reallocation of some India–Europe capacity towards growing Latin American flows. Blank sailings, rolled cargo and fluctuating allocations are adding further pressure.

But operational disruption at India’s major gateways is also playing an important role. Congestion at Nhava Sheva and Mundra has reduced vessel productivity and complicated cargo flows, while active monsoon conditions create further uncertainty for port operations and inland road and rail connections.

That matters because weather disruption is increasingly becoming an interconnected supply chain risk rather than simply a temporary port problem. Across Asia, tropical storms and extreme rainfall are affecting manufacturing, inland transport, terminals and vessel schedules simultaneously. A disruption at origin can then propagate through subsequent port calls and connections long after local conditions improve.

For exporters in India and Bangladesh, that combination makes early planning increasingly important. Securing space, allowing realistic lead times and retaining flexibility over gateways, routings and transport modes can provide valuable protection when capacity tightens or weather interrupts established schedules.

Metro combines extensive operations in India and Bangladesh to give shippers more options when ocean capacity becomes constrained. From securing vessel space and monitoring equipment availability to alternative routings, airfreight and air/sea solutions, we can identify pressure points early and build the flexibility your supply chain needs to keep critical cargo moving.

When capacity is scarce and disruption can develop quickly, talk to Metro before your shipment becomes urgent. EMAIL Managing Director Andrew Smith today

Nhava Sheva

Customer Advisory: India and China Container Shipping Disruption

Container shipping markets in India and China are experiencing significant operational disruption, resulting in longer transit times, reduced schedule reliability, constrained equipment availability and rising freight costs.

Metro is working closely with shipping lines, terminals and inland partners to minimise disruption and identify practical alternatives for affected cargo. Customers are advised to plan shipments as early as possible and allow additional time throughout their supply chains.

India market update

The Indian container market is under sustained pressure across both export and import supply chains.

A combination of strong export demand, restricted carrier capacity, equipment shortages and ongoing congestion at key gateway ports is making vessel space increasingly difficult to secure. These conditions are contributing to vessel rollovers, revised sailing schedules, extended transit times, peak season surcharges (PSS) and highly volatile freight rates.

The India–US and Latin America trades remain under the greatest pressure, particularly for cargo moving to the US East Coast.

Freight rates and surcharges

Spot-market freight levels for India–US East Coast shipments are currently ranging from approximately USD 10,000–12,000 per 40HC, depending on port pairing, routing and available capacity.

Carriers continue to introduce Peak Season Surcharges for both spot and contract cargo. These charges increased through August, with further increases being announced for September.

On the India–US East Coast trade:

  • Average August PSS levels are around USD 5,000 per 40HC
  • Maersk has announced a PSS increase to USD 7,500 per 40HC, effective 1 September
  • Further PSS increases remain possible across other India export markets

Rate volatility is expected to continue into September as carriers maintain tight capacity controls and place further pressure on allocations.

Port congestion and equipment availability

Active monsoon conditions are affecting port operations and inland transport across India’s west coast. The disruption is expected to continue in the near term and may cause further delays to container movements, terminal operations, rail services and road transport around major gateways. 

Major Indian gateways, particularly Nhava Sheva/JNPT, continue to experience congestion caused by vessel bunching, terminal capacity pressure, rail delays and limited transport equipment availability.

Key gateways potentially affected include:

  • JNPT / Nhava Sheva: India’s busiest container gateway and a major export hub for US-bound cargo
  • Mundra: India’s largest private container port, handling significant volumes of US-bound exports
  • Hazira: An important feeder and export gateway for manufacturing cargo from Western India

Container availability, particularly for 40HC equipment, remains inconsistent at several export locations. This may delay booking confirmation and require longer lead times for exporters.

Customers should anticipate additional variability in shipment timing, particularly where cargo depends on inland positioning or feeder connections.

China port disruption

Typhoon Dolphin has created further disruption at Chinese ports following the impact of Typhoon Bavi just weeks earlier.

The storm brought heavy rain and strong winds to Zhejiang province before moving on as a tropical storm. Authorities have warned of continued risks from torrential rain, flooding and landslides, while flight cancellations and transport disruption have also affected the wider region.

Port and vessel impact

Temporary closures at Shanghai, Ningbo-Zhoushan and surrounding feeder ports disrupted cargo handling and vessel movements.

Current impacts include:

  • Vessels delayed, held at anchorage or diverted to alternative ports
  • Service schedules changing at short notice
  • Delays of 7–21 days remaining common on affected services, with some potentially longer
  • Ongoing congestion as terminals process accumulated cargo
  • Localised disruption to rail, road and barge transport, despite conditions gradually improving

Port productivity is beginning to recover in some locations, but congestion and schedule disruption are expected to persist while backlogs are cleared.

Metro will continue to monitor developments closely and work with carriers and partners to secure capacity, explore alternatives and keep customers informed of material changes.