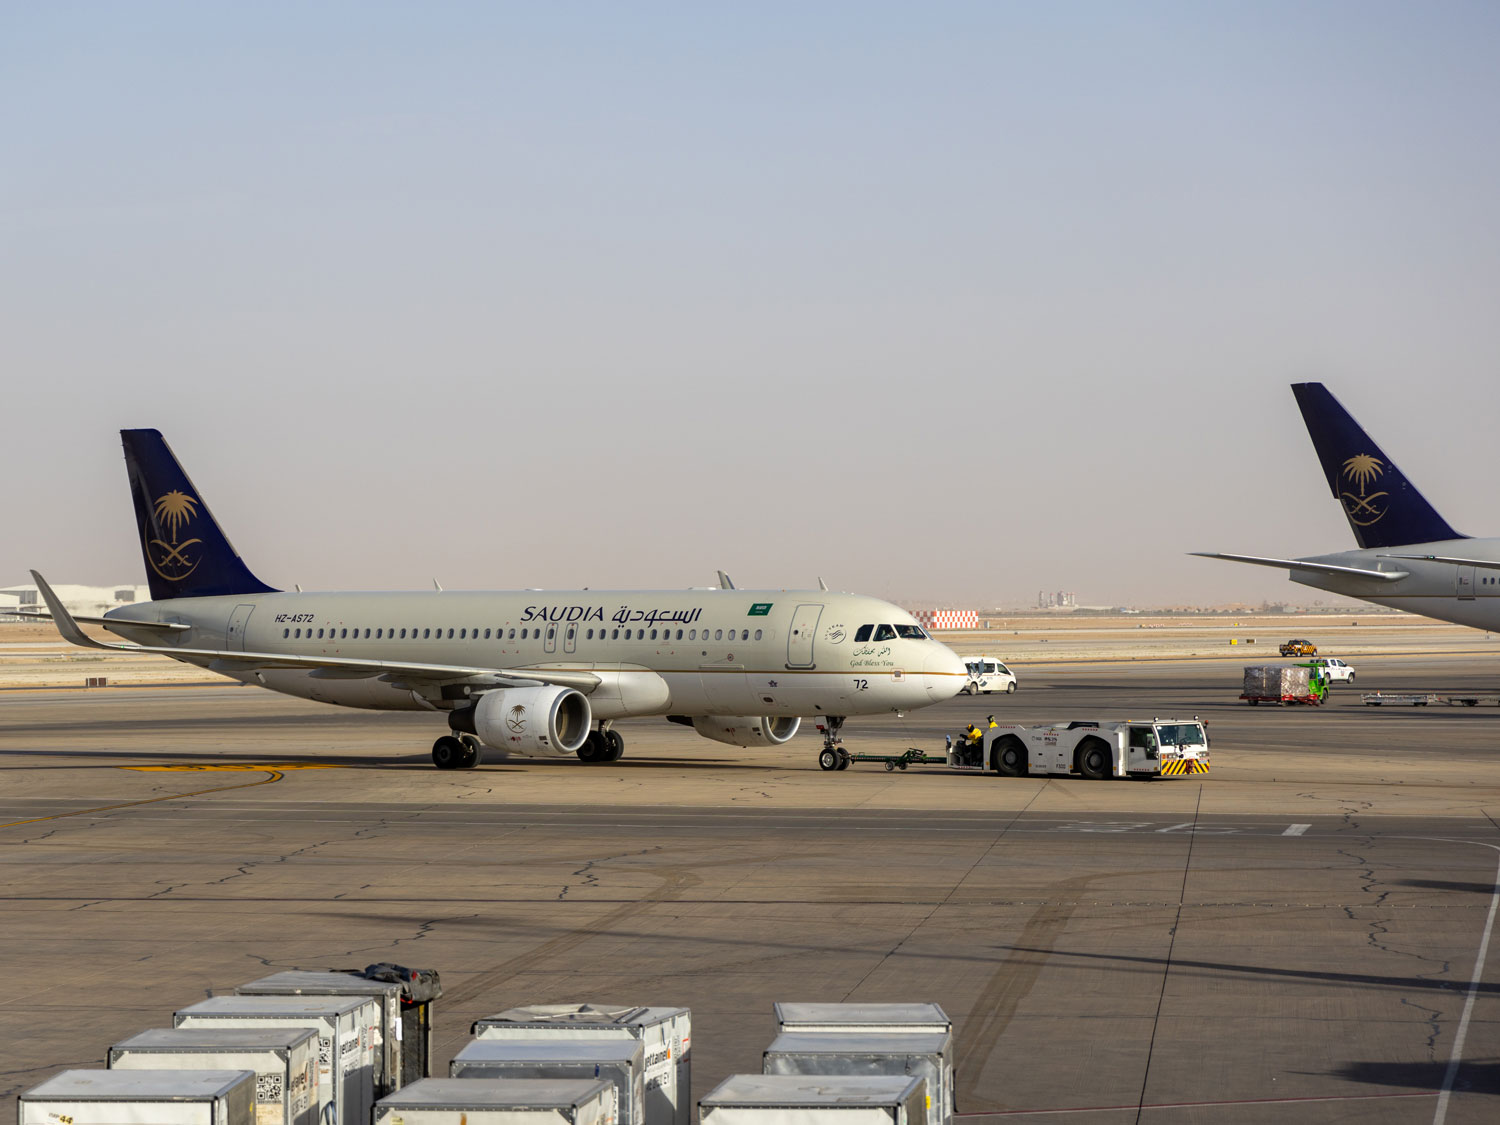
Saudia air

Airfreight demand and Middle East disruption tighten peak-season

Airfreight markets are entering the fourth-quarter peak season with demand strengthening, capacity tightening on key routes and renewed disruption in the Middle East adding pressure to airline networks and transport costs.

Global air cargo demand recovered strongly in September, with worldwide tonnages increasing 9% year on year, according to WorldACD. Growth was particularly strong across Asia Pacific and North America, where volumes increased 10%.

The recovery reflects continued demand for high-value and time-sensitive shipments, particularly equipment supporting artificial intelligence, data centres and semiconductor manufacturing.

However, the market is becoming increasingly uneven, with trans-Pacific demand accelerating, China–Europe volumes recovering only gradually and Middle East disruption affecting available capacity.

Peak-season demand strengthens despite temporary rate dip

Airfreight rates edged higher throughout September as shippers prepared for the traditional fourth-quarter peak.

Worldwide average rates increased 1% month on month and stood 25% above September 2025 levels, reflecting stronger demand, elevated fuel costs and continuing capacity constraints.

The Baltic Air Freight Index subsequently rose 5% in the week to 5 October before easing 2.1% during China's Golden Week holiday, when factory closures temporarily reduced export volumes.

Despite that decline, the index remained 24.3% higher year on year as the market entered its busiest quarter.

Capacity commitments are already influencing the outlook. Major e-commerce operators and businesses preparing product launches have secured peak-season space, while some large AI infrastructure customers have yet to finalise their requirements.

Additional bookings from these shippers could tighten available capacity and push rates higher during the coming weeks.

AI infrastructure drives trans-Pacific growth

The expansion of AI infrastructure has become a significant driver of air cargo demand, particularly between Asia and North America.

Large volumes of servers, semiconductors, data-centre equipment and energy storage systems are moving from manufacturing centres in Taiwan, South Korea, Vietnam and China to support US investment in digital infrastructure.

Trans-Pacific airfreight volumes increased 10% year on year in September, with outbound Asian load factors approaching 90%, despite airlines increasing capacity by approximately 10%.

The strength of demand is also influencing airline deployment decisions, with freighters being transferred from other routes to serve the trans-Pacific market.

WorldACD figures reinforce the trend, showing China–US air cargo tonnages increasing 17% year on year in September, while average spot rates rose approximately 30%.

Ocean freight disruption could add further pressure. Schedule reliability from Asia to the US West Coast reportedly fell from 56% in May to just 26% in September, increasing the potential for urgent shipments to transfer to airfreight.

Saudi attacks create further capacity uncertainty

Renewed attacks on Saudi Arabian airports have introduced another source of disruption as the peak season gathers pace.

Following strikes on Riyadh's King Khalid International Airport and other Saudi facilities, airlines suspended services and authorities imposed operational restrictions.

Initial data showed Riyadh's international outbound air cargo capacity falling 34% over 24 hours, with freighter capacity particularly affected.

Further attacks prompted an extended suspension of operations at Riyadh on 12 October, while Dammam International Airport also experienced disruption.

The immediate consequences extend beyond Saudi Arabia. Airlines operating between Asia and Europe have already been adjusting their networks following wider Middle East disruption, including the loss of established intermediate stops.

Alternative routings can increase flying times, introduce payload restrictions and reduce the effective capacity available to shippers.

With peak-season demand building, prolonged restrictions could intensify competition for available space, particularly on routes connecting Asia, the Middle East and Europe.

China–Europe recovery remains uneven

While trans-Pacific demand continues to strengthen, the China–Europe market presents a different picture.

Combined air cargo volumes from mainland China and Hong Kong to Europe fell 10% year on year in September, although this represented an improvement on declines of 14% in July and 15% in August.

The downturn reflects changes to EU treatment of low-value e-commerce imports, which have affected shipments from Hong Kong and southern China.

Hong Kong–Europe tonnages remained 24% below September 2025 levels, while mainland China recorded a more modest 2% decline.

Rates have reflected this divergence, with China–Europe average prices increasing approximately 9% year on year in September, compared with a 30% increase in China–US spot rates.

The figures highlight how demand, regulation and available capacity are creating increasingly different conditions across major airfreight corridors.

Planning ahead as capacity tightens

The fourth-quarter outlook points towards sustained demand, particularly on trans-Pacific routes, with further potential for rate increases as remaining peak-season capacity is committed.

Saudi Arabian disruption adds uncertainty to an already constrained market, while higher fuel costs and shifting airline networks could affect availability and pricing across other trade lanes.

For shippers, early planning, accurate forecasts and flexibility over routing and departure dates will be increasingly important.

Metro's global airfreight network, airline relationships and experienced operational teams help customers secure capacity, assess alternative routings and respond quickly when market conditions change.

Whether managing regular shipments, urgent requirements or time-critical cargo, Metro combines international buying power with local expertise and shipment visibility to keep supply chains moving.

Contact Metro's airfreight team to review your peak-season requirements, protect critical shipments and identify the most effective options before capacity becomes constrained.
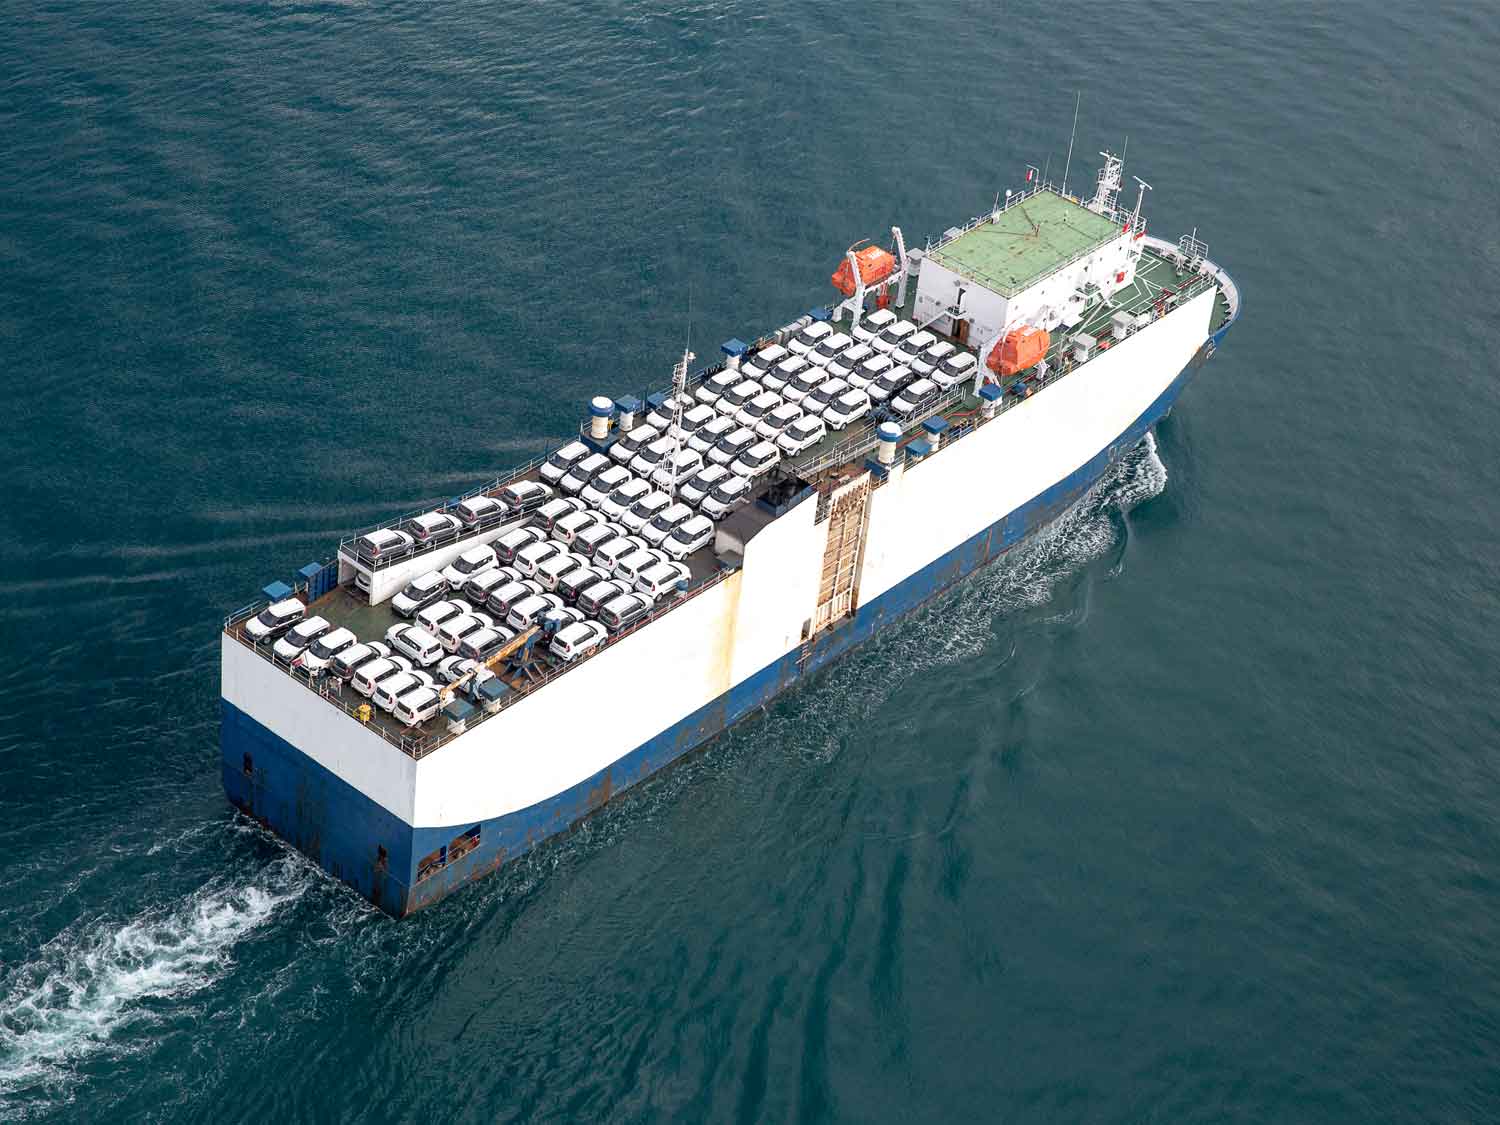
RoRo PCC

Car carrier expansion opens opportunities for European exporters

Surging Chinese vehicle exports are driving a new wave of car carrier investment, while European operators expand their fleets and develop more versatile vessels, creating potential opportunities for UK and European exporters.

The global car carrier market is entering another period of expansion, with shipping lines and automotive manufacturers investing in larger, more efficient vessels to meet growing demand.

China is driving much of this investment, as its automotive exports continue to increase and manufacturers seek greater control over international distribution.

However, European shipping operators are also expanding their fleets, investing in new technology and developing more flexible cargo-carrying capabilities.

For UK and European exporters, these developments could eventually improve vessel availability and create new international shipping opportunities.

Chinese exports drive record investment

China's vehicle exports now exceed one million units per month, creating sustained demand for dedicated car carrier capacity.

Cosco Shipping, BYD and SAIC Anji Logistics are planning a combined investment in 21 vessels, each capable of carrying approximately 11,000 cars.

Elsewhere, Global Car Carriers has ordered eight additional 8,600-car vessels for delivery in 2029 and 2030.

The global car carrier order-book now represents approximately 27% of the active fleet, with 2026 potentially setting a new record for vessel orders.

Despite this investment, capacity remains constrained. Some operators have been unable to accommodate all available cargo, while an estimated three million Chinese vehicles could move in containers this year because of insufficient dedicated car carrier space.

European operators invest in capacity and versatility

The expansion is not confined to Chinese operators. European shipping companies are also investing in larger, more efficient vessels, including multipurpose roll-on/roll-off ships capable of transporting vehicles, trailers, containers and high-and-heavy equipment.

Grimaldi is developing a new generation of larger, more fuel-efficient container/RoRo vessels, alongside multipurpose ships designed to accommodate a wider range of automotive and industrial cargo.

The programme builds on its existing fleet expansion and reflects growing demand for flexible international shipping capacity.

CLdN has ordered two additional ro-ro vessels for delivery in 2029, designed to improve fuel efficiency by 30–40% compared with smaller ships in its existing fleet.

Stena RoRo is also expanding its E-Flexer programme, with two further vessels scheduled for delivery in 2030.

Operators are not simply adding capacity. They are investing in vessels that can carry more cargo, accommodate different vehicle types and improve operational efficiency.

Changing trade flows create export opportunities

China's automotive export growth is also reversing established shipping patterns.

Historically, European manufacturers generated substantial finished vehicle volumes moving eastwards to Asian markets.

Today, Chinese manufacturers are generating increasing westbound volumes, leaving some vessels with comparatively limited cargo for their return journeys.

For UK and European exporters, this imbalance could create opportunities to secure space on returning vessels.

Additional capacity may support exports of finished vehicles, commercial vehicles and specialist automotive cargo, although availability will depend on individual vessel rotations, port calls and destination markets.

Trade policy could also influence future capacity deployment, with recent EU restrictions on Chinese hybrid vehicle imports potentially redirecting shipments towards other international markets.

While the immediate market remains tight, new vessel deliveries and changing cargo flows could gradually improve shipping options for European manufacturers.

Turning capacity growth into export advantage

For automotive exporters, the opportunity extends beyond securing additional vessel space.

Larger ships, more versatile cargo capabilities and evolving carrier networks could provide greater flexibility in selecting routes, managing costs and coordinating international vehicle distribution.

However, identifying available capacity and matching it to specific export requirements will remain essential.

Metro's specialist automotive logistics team combines established carrier relationships with expertise in finished vehicle movements, multimodal transport and international distribution.

As shipping networks evolve, Metro can help manufacturers and exporters assess emerging capacity, identify alternative routings and develop efficient transport solutions.

Put changing automotive shipping patterns to work for your business. Talk to Metro's automotive specialists about securing capacity, improving routing options and strengthening your international vehicle supply chain.

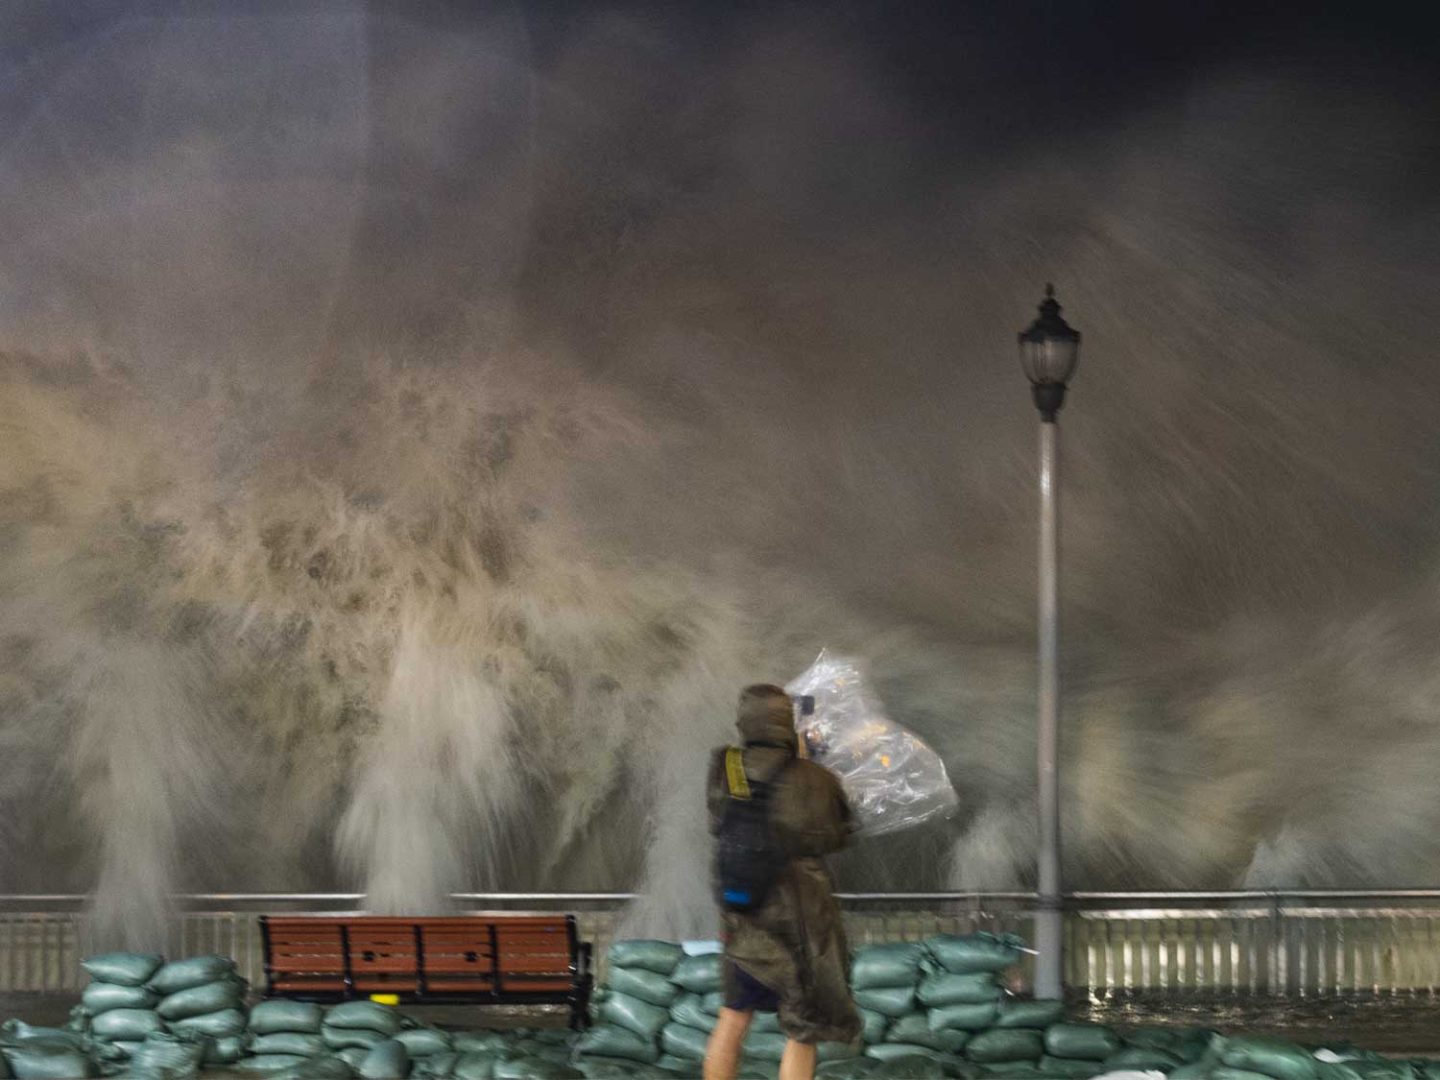
Typhoon HKG 1440x1080 1

Supply chain resilience moves from response to strategy

Supply-chain leaders meeting in London have highlighted a significant shift in priorities, as resilience, visibility and flexibility move from operational concerns to strategic business requirements.

Recent years have tested international supply chains through pandemic disruption, port congestion, geopolitical conflict, Red Sea diversions, changing trade policies and extreme weather.

But one of the clearest messages from Supply Chain LIVE: The London Summit 2026 was that businesses are moving beyond reacting to individual disruptions and increasingly designing supply chains that expect change.

Some 2,500 attendees gathered at London's QEII Centre, with discussions spanning resilience, artificial intelligence, sustainability, global trade and supply-chain orchestration.

Contributions from senior executives at Siemens, Tate & Lyle, Babcock International, Kongsberg Maritime and other organisations highlighted how supply-chain management is evolving from an operational function into a strategic business capability.

Supply chain has become a boardroom issue

Supply-chain management was once primarily judged through operational measures: cost, inventory, lead time and service. Those measures remain important, but supply-chain decisions now have wider commercial implications.

Availability can determine whether production continues. Sourcing decisions influence exposure to geopolitical and tariff risks. Transport costs affect margins, while sustainability performance increasingly depends on information from suppliers and logistics networks.

Speaking about supply chain as a strategic growth engine, Tate & Lyle's Chief Supply Chain Officer, Kim Faulkner, emphasised the importance of looking beyond operational metrics to understand the wider business outcomes they enable.

Similarly, discussions on global trade and logistics highlighted how business continuity and strategic decision-making have brought supply chain into the boardroom.

That reflects what Metro is seeing across international freight.

Businesses are no longer asking only how cheaply or quickly goods can move. They are considering what happens when a preferred route, carrier, supplier or transport mode becomes unavailable.

Resilience increasingly means having options

Recent disruption has demonstrated how quickly established transport patterns can change.

Red Sea diversions have absorbed significant container capacity, while Asian weather disruption and port congestion have affected vessel schedules and reduced effective capacity across shipping networks.

The result is an important distinction between capacity that theoretically exists and capacity actually available when and where shippers need it.

During the summit's discussion on supply-chain risk and resilience, Babcock International's Ewan Sime observed that many risks are not necessarily new, but the ways they emerge and affect businesses are changing.

This reinforces the need to prepare for different outcomes rather than attempt to predict every disruption.

Building resilience does not necessarily mean maintaining expensive inventory buffers or accepting permanently higher logistics costs.

It means creating alternatives before they become necessary.

Different carriers and gateways can provide options when services are disrupted. Consolidation can offer alternative routes to market, while airfreight can protect urgent shipments when ocean schedules become unreliable. Road, rail and multimodal solutions provide further flexibility.

More efficient routing, better utilisation and consolidation can also reduce unnecessary movements, supporting sustainability objectives while improving operational performance.

The challenge is identifying and developing these options before disruption occurs, rather than searching for solutions when capacity is already constrained.

Visibility has to lead to action

Technology featured prominently throughout the London summit, particularly artificial intelligence and supply-chain orchestration.

AI can process information faster, digital platforms improve visibility, and automation removes repetitive processes. But knowing where cargo is located is only the beginning.

The real value comes from combining information with the ability to act on it.

That distinction was reflected in Kongsberg Maritime's presentation, From Visibility to Resilience, where senior executive Rob Anthony emphasised the growing importance of adaptability and flexibility in responding to supply-chain risks.

A delayed vessel notification has limited value without an alternative. Identifying congestion matters more when another gateway can be considered. Anticipating tightening capacity becomes useful when space can be secured before conditions deteriorate.

International supply chains remain complex networks of carriers, ports, suppliers and transport providers operating across different countries and regulatory environments.

The summit also reinforced the continuing importance of people. Siemens' Alexander Tschentscher highlighted the essential role of people in delivering effective supply-chain operations, even as technology becomes more sophisticated.

When disruption occurs, established relationships, experience and local knowledge remain essential.

Metro's technology provides customers with greater visibility and control across international movements, while its operational teams combine market intelligence, carrier relationships and local expertise to identify changing conditions and potential alternatives.

Technology can highlight a problem. Experience and operational flexibility help resolve it.

Globalisation is changing rather than disappearing

Resilience is also influencing where businesses source and manufacture.

Companies are reassessing dependence on individual countries, suppliers and trade lanes, supporting increased interest in India, Turkey, North Africa and manufacturing closer to end markets.

But diversification does not necessarily mean de-globalisation. New manufacturing locations create new trade flows, often introducing additional logistics requirements and infrastructure challenges.

India provides a good example. Its expanding manufacturing and export economy offers significant opportunities, but rapid growth is also putting pressure on vessel capacity, container equipment and inland infrastructure.

Metro's expanding presence in India provides greater local visibility and connectivity as customers consider the country both as an alternative sourcing location and a growing consumer market.

The same principle applies elsewhere. Supply chains are becoming more geographically diverse, increasing the importance of local knowledge, reliable transport connections and coordination across international networks.

From reacting to disruption to designing for it

Perhaps the most significant change in supply-chain thinking is the recognition that disruption is no longer exceptional.

The causes may change – weather, geopolitics, congestion, tariffs or labour shortages – but volatility has become a recurring feature of international trade.

Businesses cannot predict every disruption, but they can improve their ability to respond through better information, earlier intervention and greater operational flexibility.

This is where Metro's long-standing investments in technology make a practical difference.

Through its digital MVT platforms, Metro gives customers greater visibility of international shipments, products flows, supply-chain performance and the intelligence needed to support more informed decisions.

Combined with Metro's global network, carrier relationships and experienced operational teams, that visibility helps customers identify emerging issues, assess alternatives and take action before disruption becomes a more significant problem.

For shippers, resilience is increasingly less about predicting the next problem and more about having the visibility, intelligence and flexibility to respond when it arrives.

Metro brings these capabilities together to help customers build more responsive, efficient and resilient international supply chains.

Forklift loading container

Asia–UK ocean market faces volatile October as capacity shifts

UK importers face an unusually volatile October as falling Asia–Europe freight rates collide with excess scheduled capacity, returning Suez services, short-notice blank sailings and continuing disruption across Asian ports.

Ocean carriers are attempting to halt a 12-week decline in Asia–Europe rates with increases planned for the second half of October. However, the traditional slowdown following China's Golden Week (1–7 October) could make those increases difficult to sustain unless carriers withdraw significant capacity.

For shippers, lower underlying demand may therefore bring temporarily cheaper freight but not necessarily more reliable supply chains.

Golden Week creates a capacity imbalance

Asia–North Europe scheduled capacity is unusually high. Around 1.5m TEU is scheduled across the four-week Golden Week period, 27% more than last year and 60% above pre-pandemic averages.

But those figures overstate the amount of genuinely new capacity entering the market.

Typhoon disruption and severe congestion at Chinese ports have pushed vessels significantly behind schedule. As delayed ships return to service alongside their normally scheduled counterparts, 12 double sailings are expected across Asia–Europe and Mediterranean services during the first two weeks of October.

At the same time, Golden Week factory closures will reduce export volumes.

The result could be a rapid shift from constrained effective capacity to temporary oversupply as delayed vessels return and cargo volumes fall.

Carriers are likely to respond with significant blank sailings, potentially announced at relatively short notice. That could leave mid-to-late October schedules particularly vulnerable to cancellations, rolled cargo and departure changes.

Suez return adds more effective capacity

The gradual return of Asia–Europe services to the Suez Canal adds another variable.

Faster Suez routings effectively release vessel capacity because ships can complete round voyages considerably faster than when sailing around the Cape of Good Hope.

Asia–North Europe services remain cautious, but the shift is gathering pace. Around 30% of backhaul capacity was using Suez during September, with this expected to reach approximately 40% in October.

Several additional services are now moving back to the canal, primarily to return delayed vessels to Asia more quickly following severe port congestion.

For UK importers, increased Suez utilisation could eventually support shorter transit times and greater capacity. In the immediate term, however, changing vessel rotations and the possibility of further network adjustments add even more uncertainty to schedules.

Security conditions in the Red Sea also remain fluid, meaning carriers retain the option of reverting to Cape routings if their risk assessments change.

Reliability remains the bigger concern

Freight rates from Asia to North Europe have been under pressure for some time, which is why carriers have announced increases for the second half of October in an attempt to reverse that trend.

But price is only part of the equation. Multiple typhoons in seven weeks created severe disruption at Shanghai, Ningbo-Zhoushan and Yantian, with berthing delays extending up to 14 days, with on-time performance on services falling to just 62% in August, while average delays for late Asia–Europe vessels reached five days.

Residual disruption is expected to continue through October as vessel bunching, accumulated container backlogs and post-Golden Week capacity adjustments work through the network.

The immediate risk for UK importers is therefore less about a shortage of nominal vessel capacity and more about whether booked capacity operates when expected.

European disruption adds another risk

Conditions at destination also require attention. German port workers are currently voting on authorisation for indefinite strike action after rejecting the latest employer wage offer. The ballot closes on 1 October, with Hamburg, Bremen, Bremerhaven and other major German ports potentially affected if industrial action follows.

German freight interests are already preparing for possible restrictions affecting terminal handling and pre- and on-carriage.

While this does not directly affect UK ports, significant disruption at major North European gateways could create wider network effects as carriers adjust rotations and cargo moves through alternative ports.

The transatlantic market is moving differently. Europe–US East Coast spot rates remain substantially above last year's levels, while carriers are managing winter capacity through blank sailings. This makes early allocation planning particularly important for exporters relying on North Atlantic services.

Flexibility will matter through Q4

October therefore presents an unusual combination for Asia–UK shippers.

Underlying rates are soft, substantial scheduled capacity is entering the market and shorter Suez routings are gradually restoring effective vessel supply. Yet congestion, poor schedule reliability and likely carrier capacity management mean the operational environment could remain unpredictable, with rates likely to harden.

Shippers should consequently avoid interpreting softer rates as a signal that the market has normalised.

Metro's established carrier relationships and extensive global network give our teams access to multiple services, routings and consolidation options across the Asia–UK trade. By monitoring capacity, schedules and gateway conditions, we can identify alternatives when blank sailings, congestion or network changes threaten planned movements.

Talk to Metro about your Q4 Asia–UK requirements and how alternative carriers, routings and consolidation options can provide greater flexibility as the market adjusts.