Ocean freight rates on Asia–Europe trades are rising again after months of downward pressure, but contrasting market indicators and increasing blank sailings suggest the recovery is being driven as much by carrier capacity management as underlying cargo demand.
The Asia–Europe container market has entered a new phase of price volatility, with shipping lines attempting to strengthen freight rates ahead of November and the approaching annual contract negotiation season.
After an extended period of softening spot rates, October has delivered two consecutive weeks of increases. However, the recovery remains uneven, with conflicting freight indexes and relatively subdued demand raising questions about whether higher prices can be sustained.
For shippers, the immediate challenge is distinguishing between genuine market tightening and temporary price movements created by changes to available capacity.
Spot rates reverse their downward trend
Drewry's World Container Index recorded a 6% increase on Shanghai–Rotterdam and a 7% rise on Shanghai–Genoa mid-October, reversing several weeks of declining prices.
The recovery continued into the following week, with Shanghai–Rotterdam increasing another 3% and Shanghai–Genoa rising 5% in the assessment published on 22 October.
Across the two weeks, this represents cumulative increases of approximately 9% and 12% respectively.
The broader Drewry index increased 2% in the latest assessment, reflecting firmer pricing across several major east–west trades.
However, not every benchmark supports the same interpretation and while Drewry recorded rising Asia–Europe rates in mid-October, another freight index reported a 7% decline on Asia–North Europe.
Different methodologies, reporting periods and underlying transactions explain some of the divergence, but the contrasting readings reinforce the absence of a consistent recovery across the market.
Shipping lines withdraw capacity to support prices
With demand showing limited signs of significant acceleration, carriers are turning increasingly to capacity management.
Drewry reported eight blank sailings scheduled on Asia–Europe services for the week beginning 26 October, compared with two the preceding week.
The broader outlook confirms that capacity adjustments will continue through November.
Across the major east–west trades, 56 sailings are expected to be cancelled between weeks 44 and 48, representing approximately 8% of the 714 scheduled departures.
Asia–Europe and Mediterranean services account for 54% of these cancellations, making them the principal focus of carrier capacity management.
Although 92% of scheduled services are still expected to operate, cancellations can have a disproportionate effect on individual departure weeks, ports and carrier networks.
For shippers, this creates a familiar contradiction: substantial overall vessel capacity alongside restricted availability on particular services.
Blank sailings can also concentrate cargo onto fewer vessels, increasing the risk of rollovers and schedule disruption.
November rate increases face a demand test
Alongside withdrawing capacity, shipping lines are introducing higher Freight All Kinds (FAK) rates.
New pricing announced for mid-October targeted increases across North Europe and Mediterranean destinations, although some offers were subsequently revised downwards.
Further increases have been announced for 1 November, with Mediterranean targets generally higher than those for North Europe.
Shipping lines are attempting to establish firmer pricing ahead of annual contract discussions, but without a sustained increase in cargo volumes, higher rates may prove difficult to maintain.
The coming weeks will therefore test whether capacity withdrawals can support the recovery or whether additional available space and competitive pricing will limit further increases.
Operational developments could also influence the balance between capacity and demand.
Asian port congestion has shown signs of improvement, with vessel waiting times at Shanghai falling from 97 hours in week 38 to 38 hours in week 42.
This improvement should help restore schedule efficiency and release vessel capacity previously absorbed by delays.
What this means for shippers
The latest developments suggest that Asia–Europe freight rates will remain volatile through the remainder of 2026. Recent increases have been supported by carrier capacity management and pricing initiatives, but subdued demand and discounted offers suggest that further fluctuations are likely.
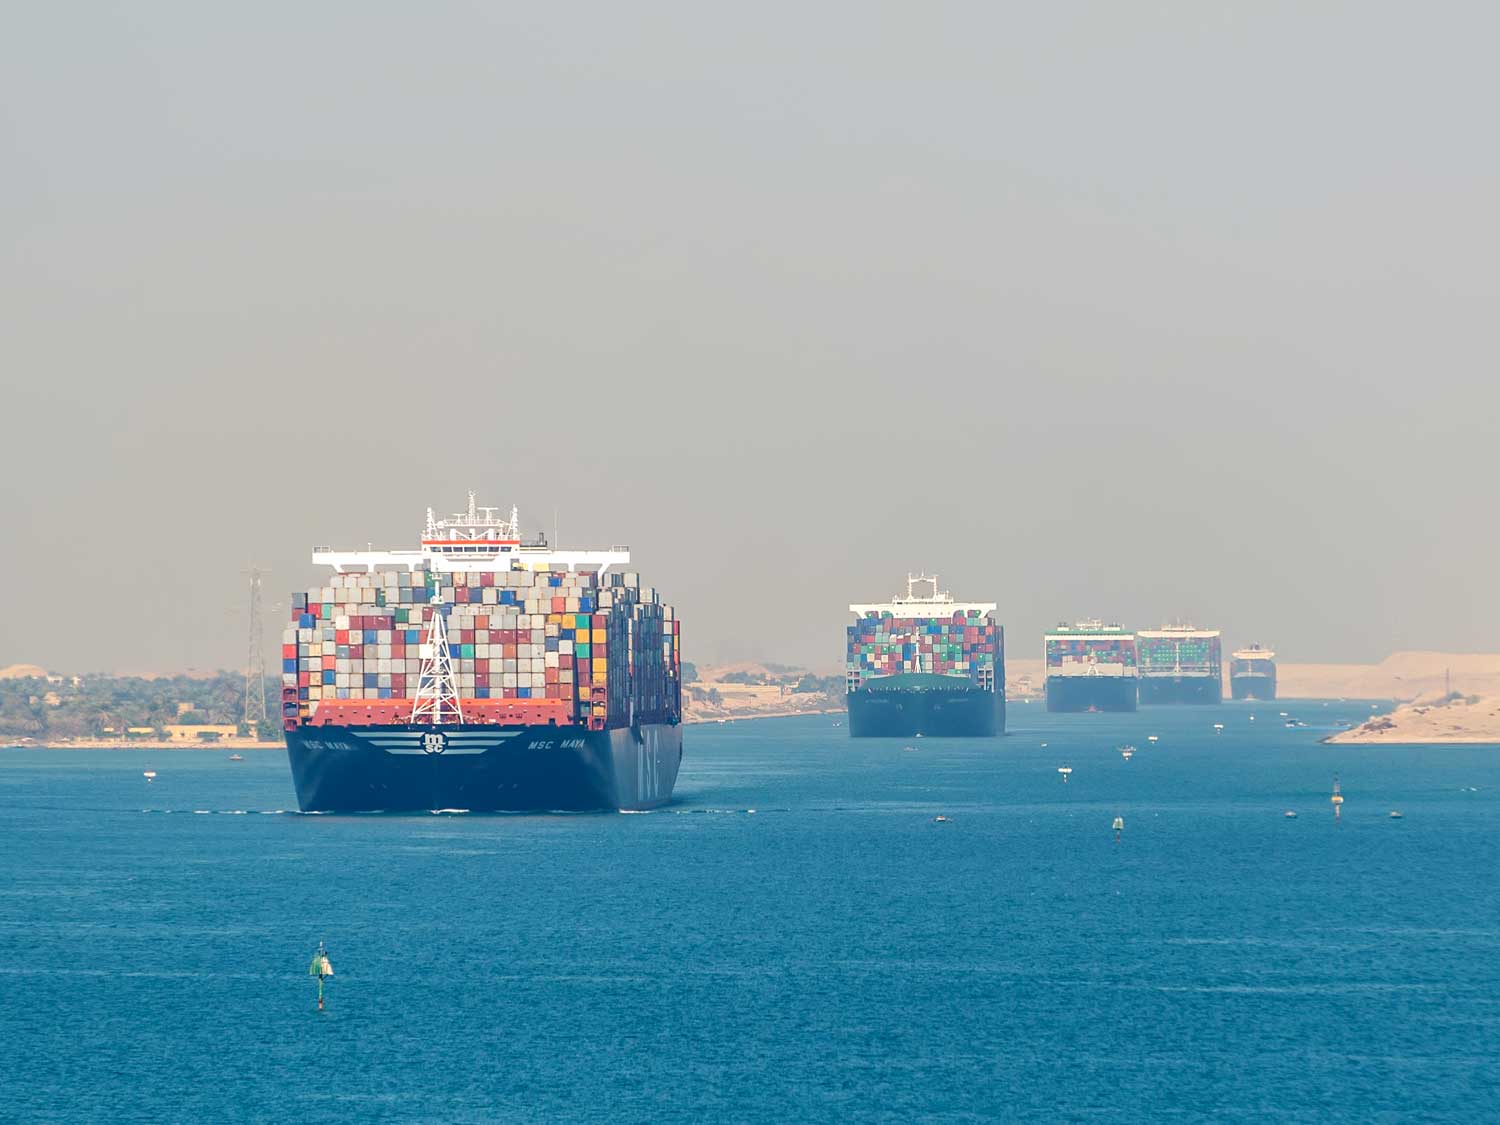
Service reliability remains just as important as pricing, with blank sailings reducing departure options and increasing the risk of cargo being rolled. Meanwhile, improving Asian port operations and the gradual return of services through the Suez Canal could release additional capacity, changing the balance between supply and demand.
Shippers should therefore assess available services, booking windows and delivery requirements alongside freight rate movements, rather than relying solely on headline market indexes.
Metro: Turning market volatility into better shipping decisions
When freight rates fluctuate and carriers adjust capacity, the lowest quoted price is not always the best shipping solution.
Metro combines established relationships with leading ocean carriers, global freight procurement expertise and extensive origin and destination capabilities to help customers make informed decisions across Asia–Europe trades.
Our teams monitor carrier schedules, capacity withdrawals, freight pricing and port conditions, identifying alternative services, gateways and consolidation opportunities when market conditions change.
Whether you're reviewing November bookings, preparing for 2027 contract negotiations or looking to improve schedule reliability, Metro can help you balance competitive pricing with dependable capacity and delivery performance.